
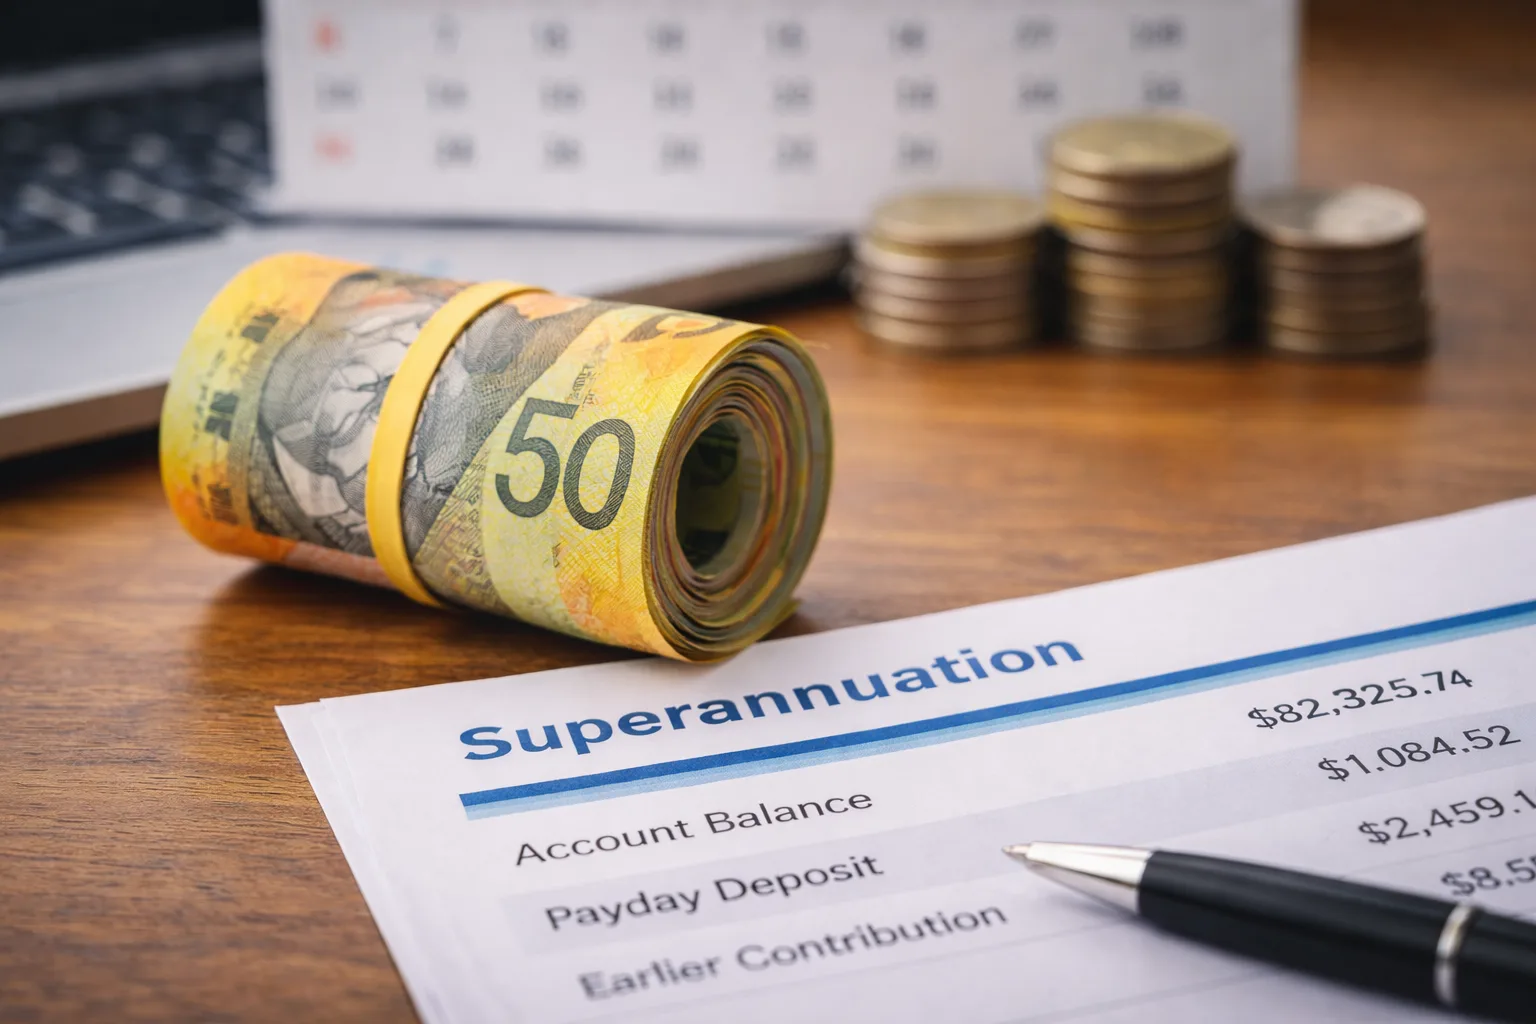
For many Australians, superannuation exists quietly in the background of working life.
It grows slowly over decades, supported by employer contributions and investment returns, but it rarely becomes part of everyday financial thinking.
Most people check their super balance occasionally. Sometimes this happens when changing jobs. Sometimes during tax season. Occasionally it appears during moments of financial reflection about the future.
But outside of those moments, superannuation often feels distant.
It is a long-term asset, designed to support retirement many years down the track. Because of that distance, it can be easy to disengage from it entirely.
However, a structural shift known as Payday Super may begin to change how Australians engage with their retirement savings.
While it may appear to be a technical change to the way super contributions are paid, the broader impact could be much more significant.
In practice, changes like this rarely stay administrative. They tend to change behaviour.
In many ways, it has the potential to reshape behaviour, awareness and long-term financial planning across the workforce.
Understanding the Move to Payday Super
Under the current system in Australia, employers are typically required to pay superannuation contributions quarterly.
This means that although super is earned alongside wages, there can be a delay between when income is received and when those contributions appear in a super account.
The proposed Payday Super system aims to align super contributions with regular pay cycles.
Instead of being paid quarterly, super contributions would be deposited into an employee’s super fund at the same time as their wages.
On the surface, this may appear to be a simple administrative adjustment.
However, when financial systems change the timing and visibility of money, they often influence behaviour as well.
And behaviour plays a powerful role in long-term financial outcomes.
Why Visibility Matters in Financial Behaviour
One of the strongest drivers of financial engagement is visibility.
When people can clearly see money moving through their financial system, they are more likely to pay attention to it.
Think about the way people interact with their bank accounts today.
Digital banking apps allow individuals to see income arrive, expenses leave and savings grow in real time. This transparency encourages awareness and accountability.
Superannuation, by contrast, has historically been less visible.
Because contributions are often delayed and balances change gradually, many Australians feel disconnected from their retirement savings.
Payday Super may begin to change this relationship.
When super contributions appear alongside each pay cycle, individuals may start to associate their retirement savings more directly with their working income.
That shift is subtle, but powerful.
That small shift in visibility can make super feel more immediate and more relevant.
A Cultural Shift in Retirement Awareness
Australia’s superannuation system is one of the most comprehensive retirement savings systems in the world.
Yet despite its scale and importance, many Australians still feel uncertain about how their super works or whether they are on track for retirement.
Many people assume their super will simply grow automatically over time.
Others postpone reviewing their super because retirement feels too far away to worry about now.
More frequent contributions may help shift this mindset.
Instead of viewing super as a distant financial asset, individuals may begin to see it as a living part of their financial system.
Greater visibility can encourage people to think more actively about:
- how much they are contributing
- how their super is invested
- whether their retirement goals are realistic
- and how super fits within their broader financial plan
Even small increases in awareness can create meaningful long-term change.
Earlier Conversations About Retirement Planning
One of the most interesting behavioural effects of Payday Super may be earlier engagement with retirement planning.
Traditionally, many Australians begin thinking seriously about retirement during their forties or fifties.
At that stage:
- career paths are more established
- income levels are clearer
- retirement begins to feel more tangible
However, by that point, valuable time for compounding may already have passed.
Small contributions made earlier in life can have a powerful impact because they have more time to grow.
If Payday Super encourages younger professionals to pay closer attention to their retirement savings, it may lead to earlier financial planning conversations.
These are often the types of questions that surface in everyday conversations, long before they are recognised as a need for advice.
These conversations may include questions such as:
- Am I contributing enough to my super?
- Is my super invested in a way that aligns with my long-term goals?
- Should I be making voluntary contributions?
- How does super interact with my broader investment strategy?
Earlier awareness does not require dramatic financial changes.
But small adjustments made early can significantly influence long-term outcomes.
The Psychology of Consistent Contributions
Behavioural finance research consistently shows that consistency plays a major role in successful financial outcomes.
Regular contributions reinforce positive financial habits.
They also strengthen the psychological connection between present decisions and future security.
Under a quarterly contribution system, super can feel episodic.
Contributions appear occasionally, which can reduce the sense of connection to the process.
With Payday Super, contributions become part of each pay cycle.
This means individuals begin to see retirement savings grow gradually alongside their income.
Over time, this rhythm can reinforce long-term thinking and encourage stronger financial habits.
A Relatable Australian Scenario
Consider Liam, a software engineer in his late twenties working in Sydney.
Like many young professionals, Liam focuses most of his financial attention on immediate priorities.
His financial system currently revolves around:
- paying rent
- managing everyday expenses
- saving for travel
- contributing to an investment account
His superannuation exists quietly in the background.
He knows it is there, but he rarely checks it.
Under the traditional system, contributions appear only a few times each year.
Because of this, Liam does not associate them closely with his salary.
Once contributions begin arriving alongside each pay cycle, something changes.
Liam begins noticing the deposits more frequently.
That visibility creates engagement.
Over time, this leads him to take small but meaningful steps:
- reviewing his super balance more often
- learning how his super is invested
- considering whether to make small voluntary contributions
None of these steps require dramatic financial change.
But over the course of decades, they can significantly influence retirement outcomes.
The biggest shift was not the policy itself.
It was the behaviour that followed.
What This Means for Employers and Business Owners
Payday Super also has implications for employers.
For many businesses, particularly small and medium enterprises, superannuation compliance has historically involved quarterly reporting and payment processes.
Aligning super contributions with pay cycles may provide several practical benefits.
For businesses, it may:
- simplify payroll processes over time
- reduce the risk of delayed super payments
- improve transparency in employee entitlements
For employees, it may:
- increase visibility of super contributions
- strengthen trust in the system
- create greater engagement with retirement savings
When employees feel confident about their long-term financial security, it can also contribute positively to workplace wellbeing and stability.
Why Strategy Still Matters
While Payday Super may improve engagement with retirement savings, it does not automatically guarantee stronger financial outcomes.
Visibility creates awareness. Strategy creates outcomes.
Superannuation is a powerful financial tool, but it is only one component of a broader financial strategy.
Important decisions still remain, including:
- how much to contribute
- how super investments are structured
- when to adjust investment risk
- how super interacts with tax planning
- how retirement income will be structured
Without guidance, individuals may overlook opportunities to optimise their super or align it with other financial goals.
Integrating Super into Long-Term Financial Planning
At Ryker, we see superannuation as one pillar of a holistic financial strategy.
Retirement planning is most effective when it integrates multiple components of a person’s financial life.
This includes:
- career income and progression
- investments outside super
- tax efficiency strategies
- risk protection and insurance
- long-term lifestyle and retirement goals
When these elements work together, individuals can build a clearer pathway toward financial independence and retirement security.
Superannuation plays an important role in that journey, but its effectiveness depends on how well it integrates with the broader financial picture.
Looking Ahead
The introduction of Payday Super reflects a broader trend within financial systems.
Transparency, visibility and engagement are becoming increasingly important.
As financial tools become more digital and accessible, individuals expect to see their money move and grow in real time.
Superannuation has historically operated behind the scenes.
Payday Super may bring it closer to the everyday financial experience of Australians.
This shift may encourage more people to engage with their retirement savings earlier and more thoughtfully.
And over time, those small shifts in behaviour can create meaningful long-term differences.
Your Next Step
If you have not reviewed your superannuation strategy recently, changes such as Payday Super may provide a useful opportunity to revisit your long-term plans.
A conversation now can help you:
- understand how your super fits within your broader financial strategy
- identify opportunities to improve retirement outcomes
- align your savings with your long-term goals
The earlier this conversation happens, the more control and flexibility you create.
If you would like guidance tailored to your situation, the Ryker team can help provide clarity and direction.
The information in this article is general in nature and does not take into account your personal objectives, financial situation or needs. Before acting on any information, you should consider whether it is appropriate for your individual circumstances and seek professional advice.

Grow & Protect Your Wealth Today
Whatever’s on your mind, we’re here to help. You’ll speak with an authorised financial adviser who’ll listen first and get to know what matters to you.
Book An Initial Conversation