Financial Advice for Veterans and People Leaving the ADF
Planning Your Money for Life After the ADF
When you leave the ADF, cover that ends at discharge, your super, any DVA payments, health cover and your income after service affect one another. We help you plan them together, alongside anyone handling a claim or your tax.
Our Financial Advice Team Is Here to Help You
Who We Help
- Members nearing separation with a date set and decisions to sort before it
- Members in a medical transition with super and any DVA payments still being decided
- Members finishing a fixed term of service and planning for civilian costs
- Recently discharged veterans working through cover, super and pay in civilian life
- Veterans weighing a DVA offer with a lump sum or fortnightly choice to make
- Veterans receiving an invalidity pension from super, planning alongside any DVA payments
- ADF partners and families planning the household’s move out of service
- Ex-serving members starting a business or a civilian career after service
- Veterans planning retirement with super, savings and any payments to bring together
We Can Help You
- Compare personal insurance options for life after service, ideally before your separation date
- Build a budget on civilian pay, with the Medicare levy and health cover included
- Weigh up a DVA lump sum or fortnightly payments against your financial plan
- Plan how a super invalidity pension and any DVA payments work together
- Look at your super options after service, with the cover in each account checked first
- Test a home loan change against any home ownership subsidy, with a mortgage broker
- Plan the money side of a second career, a business or a year of study
- Map retirement income from super, any DVA payments and any Centrelink payment
- Set out investment options for any lump sum you won’t need for some years
- Work alongside any ex-service advocate, super fund or accountant helping you
What to sort first
Leaving the ADF: The Decisions in the Order They Arrive
Before Your Separation Date
As your last day in uniform gets closer, which money decisions should come first?
Putting the decisions in order can give each one the time it needs and help you leave service with a clear plan.
We’ll set out the decisions that come before your last day, in the order they need attention.
Ex-service organisations offer free or low-cost advocates who can help you prepare and lodge any claim with the Department of Veterans’ Affairs (DVA). Open Arms, Veterans & Families Counselling, offers free and confidential support 24 hours a day on 1800 011 046 for current and ex-serving ADF members and their families.
Before your last day, together we’ll look at:
- A list of the decisions ahead, from cover and super to housing, health cover and any DVA claim
- Defence’s transition checklist read alongside your money decisions, so each one has its place
- Applications for any new personal cover started early, since an insurer decides each one and its terms
- Medicare registration completed before you leave, so it’s ready to use once you’ve transitioned out
- Where you’ll live after service, and what rent or repayments will cost without any service housing or rent assistance
- Any DVA claim for a service-related condition, which a free or low-cost ex-service advocate can help you prepare
- A transfer to the Reserves, if you’re considering one, and how it changes the decisions ahead
- Documents gathered for a first meeting, such as payslips, super statements and any letters from Defence or DVA
Moving to the Reserves? Learn more about Financial Planning for Defence Force Members
Cover When Service Ends
Once you’re out of uniform, how could your income be protected if illness or injury stopped your work?
Income protection can pay part of your income after a waiting period, subject to the policy’s terms, helping with everyday costs.
We can review the cover you’d want once service ends and help you apply, ideally before your separation date.
The death and invalidity cover provided while you serve ceases when you leave the Australian Defence Force, and Defence suggests having any private cover in place before your transition date. Default cover inside super can usually be issued without medical checks, though it may carry pre-existing condition rules set out in the fund’s PDS. Any cover you apply for beyond a fund’s default cover is assessed on your health when you apply, and the insurer decides.
Together, we’ll work through:
- Life, TPD and income protection needs worked out for life after service, before any application goes in
- Default cover in a civilian fund, and any pre-existing condition rules set out in its PDS
- How income protection would sit alongside any DVA incapacity payments, as policy terms on other income vary
- Any service-related condition on an application, which an insurer can accept, load, exclude, defer or decline
- Cover held in a civilian super fund, and what may happen to it if you change or close that fund
- Who would receive any life cover or super, with each nomination reviewed for the people you’d choose today
- Cover owned inside or outside super, weighed on premiums, tax and how each policy would pay
- Trauma cover held outside super, since new trauma cover can’t be held inside super
Medical Transition and Invalidity Benefits
If health is the reason for leaving service, how do you plan with so much still being decided?
Seeing how each payment could fit together can give you a steadier plan while decisions are made.
We can explain how a super invalidity classification and any DVA payments could work together in your plan.
The military super trustee behind the invalidity cover you held while serving classifies any invalidity benefit, whichever fund you chose, and generally only the two higher classes attract a pension, which is generally taxed, with an accountant confirming how. DVA uses different tests, and its payments can be offset by super invalidity benefits, so super back pay can mean a DVA overpayment. The trustee and DVA decide eligibility, and you generally have 30 days to ask the trustee to reconsider.
What we look at with you:
- Your invalidity classification, and whether a pension from super could follow after discharge
- Any invalidity pension, which is generally taxed, with the amount confirmed by an accountant
- DVA payments and super invalidity benefits side by side, since DVA payments can be offset by super invalidity benefits
- Back pay from super that may mean a DVA overpayment, planned for before the money is spent
- Cashflow while decisions are pending, built on the income you can count on now
- Any reconsideration you ask the trustee for, with your plan kept flexible until the decision is made
- Invalidity benefits from super, which can generally be accessed as soon as military service ends
- Any lump sum from super or DVA, and where to hold it while the longer-term plan is settled
DVA Payments and the Choices They Bring
When a choice about payments can’t be changed later, how do you know which suits your life?
Comparing each option against your income, goals and the years ahead can help you choose the one that fits life after service.
We can weigh up a lump sum against fortnightly payments with you, before the time to choose runs out.
From 1 July 2026, all new compensation claims are decided under one set of rules, whenever you served. If DVA offers permanent impairment compensation, it’s paid fortnightly unless you choose a lump sum within six months of the offer, which DVA can extend in special circumstances, and that choice is final. DVA says these payments are tax-free, and at 50 or more impairment points it can reimburse advice costs on the choice up to the set limits, not above them.
The choices we weigh up together:
- A lump sum or fortnightly payments, compared against your income needs and goals over the years ahead
- A combination of lump sum and fortnightly payments, where your level of impairment allows one
- The six months DVA allows from its offer, with your options worked through before the choice closes
- Any lump sum you choose, with options to hold, invest or reduce debt set out side by side
- How a lump sum may count for some Centrelink or DVA income support payments, as DVA explains
- Reimbursement of advice costs from DVA where you’re eligible, such as at 50 or more impairment points
- The choice between a Special Rate Disability Pension and incapacity payments, if DVA asks you to make one
- Tax on each DVA payment, confirmed by an accountant, noting DVA states permanent impairment payments are tax-free
Investing a lump sum? Learn more about Tax & Wealth Strategies
Your Super After Service
For the years after you leave, how would you like the super you built in service to support you?
Looking at your options now can help your super suit the life you plan after service.
We’ll go through your super options after service, with any cover in each account checked first.
Preservation age is 60 for anyone born from 1 July 1964, and super can generally only be accessed once you meet a condition of release, such as ceasing employment at 60 or over. If you were in a closed military scheme, its own rules decide when and how a benefit is paid. For 2026-27, a civilian employer generally pays super of at least 12% of qualifying earnings.
Together, we’ll go through:
- The fund you had in service, if it stays open to you, or another, compared on fees, options and cover
- Insurance attached to each super account, checked before any account is closed or rolled over
- A closed military scheme’s benefit, if you were in one, and the choices its rules allow
- Salary sacrifice through any new employer, weighed against your take-home pay and the concessional cap
- Your investment option, set to match the years until you plan to draw on super
- Accounts from before or after service, brought together only once fees, cover and features are compared
- Personal contributions if you’re self-employed after service, with any tax deduction confirmed by an accountant
- When you can reach accumulation super, and what preservation means for money you need sooner
Civilian Costs and Your Budget
Which everyday costs will be new once service no longer covers them?
A budget built on civilian pay and costs can show what you’ll spend and what could go towards what matters to you.
We can build a budget for civilian life, with the Medicare levy, health cover and housing included.
While you’re entitled to free Defence medical care, a full or half Medicare levy exemption can apply, and the levy generally applies once you leave. Without private hospital cover, the Medicare levy surcharge can also apply above an income threshold. If you leave after the 1 July following your 31st birthday, you generally have 1,094 days from discharge to take out hospital cover at the base rate. Health and dental costs Defence covered also become part of your budget.
What we plan into your budget:
- The Medicare levy on civilian pay, which an employer generally withholds along with income tax
- Private hospital cover, timed against the days you have after discharge before a loading applies
- The Medicare levy surcharge, which can apply above an income threshold without private hospital cover
- Dental, optical and other health costs that Defence covered, planned into the budget from the start
- Salary packaging, which not every civilian employer offers, and your take-home pay with and without packaging
- Unused annual leave paid out when you leave, generally part of that year’s taxable income, confirmed by an accountant
- A cash buffer for any gap between your last Defence pay and a first civilian pay
- Tax set aside from each payment if you become self-employed, with the amount confirmed by an accountant
Housing and Your Home Loan
Once postings are behind you, how will you decide where and how to live?
Testing rent, a purchase or any loan you hold against your budget can show which home suits your plans after service.
We’ll look at where you’ll live after service, and how any home loan or subsidy fits your plan.
Leaving any service housing or rent assistance can change what you spend each fortnight. If you have or can access a home ownership subsidy, only one final certificate is available after your last effective service date, it expires after 12 months, and significant changes to your loan may stop subsidy payments, so it’s worth asking the scheme to confirm the effect before you change anything. Any new loan or refinance goes through a lender, and a mortgage broker can help.
The decisions we weigh up together:
- Rent or repayments where you plan to settle, once any service housing or rent assistance ends
- Buying or renting after service, compared on cost, flexibility and how long you expect to stay
- Any home ownership subsidy, and the one final certificate available after your last effective service date
- Refinancing a subsidised loan with a mortgage broker, after the scheme confirms whether the change may stop payments
- A deposit for a home where you settle, if buying is part of your plan
- Repayments tested against civilian pay, with a mortgage broker arranging any loan and a lender deciding
- A home you keep and rent out after moving, with the tax position confirmed by an accountant
- Costs of the move itself, such as a rental bond or stamp duty, set aside ahead of time
Keeping a home as a rental? Learn more about Property Investment Advice
Your Next Career or Retirement
After service, what would you like work, or life without work, to look like?
Planning income, super and savings around your next step can help you move into it with your finances ready.
We can plan the money side of your next step, whether that’s a civilian role, a business, study or retirement.
Base pay and allowances in service are replaced by a civilian salary, business income or a mix of payments, and a first civilian pay can take time to arrive. If you become self-employed, setting money aside for tax helps, with an accountant advising on the amount. Later, retirement income can come from super, any DVA payments and Centrelink, and we can review the plan with you as income settles.
Together, we’ll plan:
- A civilian salary offer compared with what you earned in service, allowances and super included
- A business after service, planned with start-up costs, a buffer and any personal cover you’ll need
- Study or retraining after service, with living costs planned for the months before full pay
- Retirement income from super, any DVA payments and any Centrelink payment you’re eligible for
- Age Pension eligibility, which Services Australia assesses under both an assets test and an income test
- Any pension from a closed military scheme, and how it fits alongside civilian work
- Part-time work or a phased finish, tested against how long your super and savings could last
- Reviews of the plan with you as civilian income, payments and goals settle
Your Transition, Worked Through Together
Cover Before You Leave
Life, TPD and income protection reviewed, with any application started before the cover provided in service ends.
Payment Choices Weighed Up
A lump sum or fortnightly payments compared against your income and goals before you choose.
Invalidity and DVA Payments Together
How a super invalidity pension and any DVA payments interact, set out in one plan.
Super After Service
Your fund, insurance and investment option compared before anything is moved or closed.
A Civilian Budget
Civilian pay set against new costs such as the Medicare levy and health care.
Health Cover Timing
Private hospital cover planned into your budget, keeping in view the days you have after discharge before any loading applies.
Your Home Loan and Any Subsidy
Rent, a purchase or refinance tested against your budget and any subsidy rules, with a mortgage broker handling the loan.
The Next Career or Retirement
A civilian role, business, study or retirement planned with income from each source in view.
Proactive, Holistic, and Experienced Financial Planning
Service in the ADF comes with its own pay, cover, housing and health care, and civilian life works differently. That can mean a lot to work through at once, and most of it can be taken in order. We’ll listen first, set out what needs attention and when, and work through each decision with you. There’s no cost for the initial conversation, and any advice after that is a paid service, with its scope and fee agreed with you in writing first.
Leaving service can change things for the people around you too, whether that’s a partner, children or parents you look out for. We can go at whatever pace suits you, prepare the figures and advice documents, and work with anyone helping you with a claim, your super or your tax. Together, we’ll help you plan for the years after service around the work, time and people that matter most to you.
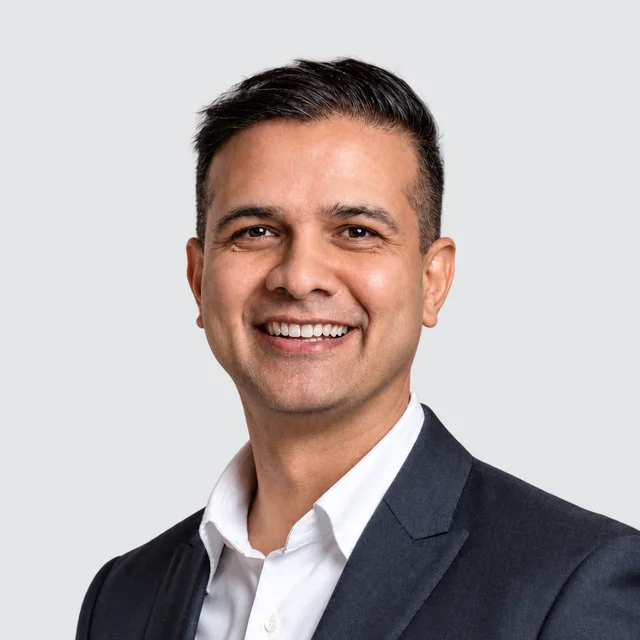
Ricky Regmi, one of our executive financial advisers, is a Major in the Army Reserve with more than 15 years of service, including a deployment to the Middle East in 2019. Supporting defence personnel is especially meaningful to him.
Every financial decision impacts the next
Your Financial Life Is Connected
Great advice starts with understanding the bigger picture. Every stage of life presents new opportunities and challenges, from buying property and changing careers to growing your family, planning for retirement and protecting what matters most. At Ryker, we help connect every piece of your financial world into one clear strategy.
Your
Wealth
- Property & Investing
- Career & Income
- Tax Strategy
- Insurance & Protecting Your Family
- Super & SMSF
- Wealth & Investments
- Life Events & Changes
- Business & Wealth
- Legacy & Future Wealth
- Retirement Planning
Frequently Asked Questions
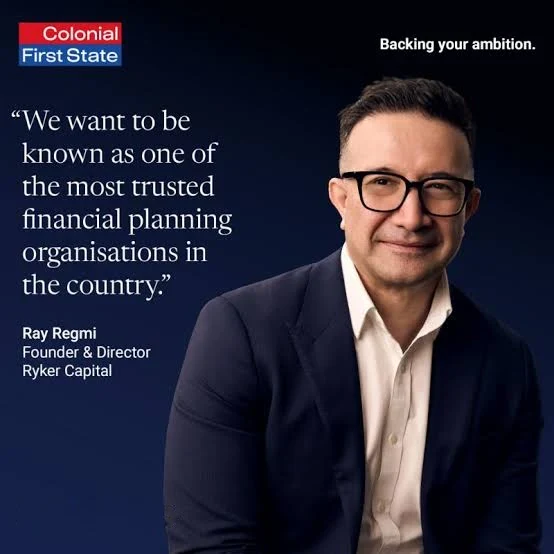
We’re invested in your long-term success. What we do is personal, and we take it personally.
Your financial decisions connect, so we consider the parts of your financial life that are relevant to the advice you need:
- Property & Investing
- Career & Income
- Tax Strategy
- Insurance & Protecting Your Family
- Super & SMSF
- Wealth & Investments
- Life Events & Changes
- Business & Wealth
- Legacy & Future Wealth
- Retirement Planning
This is how we help you make decisions today with your longer-term goals in view.
Everybody’s situation is different, so we listen first, understand what matters to you and explain your options clearly before we make a recommendation.
Yes, the death and invalidity cover provided while you serve ceases when you leave the ADF, and Defence suggests having any private cover in place before your transition date. You or your family may also be eligible for DVA benefits, which DVA assesses separately.
Default cover inside super can usually be issued without medical checks, though it may carry pre-existing condition rules set out in the fund’s PDS. Any cover you apply for beyond a fund’s default cover is assessed on your health when you apply, and the insurer decides. We can work out the cover you’d want after service and help you apply, ideally before your separation date.
It depends on your income needs, goals, debts and how you’d use a lump sum, and neither option suits everyone. If DVA offers permanent impairment compensation, it’s paid fortnightly unless you choose a lump sum, or a combination where your level of impairment allows, within six months of the offer. DVA can extend that time in special circumstances, and the choice is final.
DVA says these payments are tax-free. At 50 or more impairment points, DVA can reimburse the cost of advice on the choice up to the set limits, and any amount above those limits can’t be reimbursed. We can compare each option against your cashflow, goals and retirement before you decide.
Online checklists and calculators from Defence, DVA and super funds can be a useful starting point for seeing what’s ahead and estimating a payment or a balance. Each one generally covers its own part of the move, and its results may not bring your cover, super, any DVA payments, health cover and civilian income together.
Advice puts those into one plan for your situation. We can work from the statements and letters you have, and test each decision against your cashflow, goals and retirement.
You may be eligible, depending on the choice you’re making. DVA can reimburse advice costs, up to set limits, for some choices its legislation requires, such as between a lump sum and fortnightly permanent impairment payments, or between a Special Rate Disability Pension and incapacity payments. Any amount above those limits can’t be reimbursed. We can explain how this may apply to you, and the scope and fee of any advice are agreed with you in writing first.
They’re assessed separately, and a super invalidity benefit can change what DVA pays. Whichever fund you chose, the military super trustee behind the invalidity cover you held while serving looks at how conditions present at discharge affect your capacity for civilian work, while DVA compensation is based on different principles, so the two can reach different results. DVA payments can be offset by super invalidity benefits, and super back pay can mean a DVA overpayment. The trustee often pays this to DVA directly from the back pay, and DVA is usually required to recover any amount the back pay doesn’t cover.
An invalidity pension is generally taxed, and an accountant can confirm how. We can plan your cashflow around both, while the trustee and DVA decide eligibility.
The Medicare levy generally applies once you leave, because its full or half exemption depends on being entitled to free Defence medical care. You can register with Medicare before you leave, ready to use once you’ve transitioned out, and without private hospital cover the Medicare levy surcharge can apply above an income threshold.
If you leave after the 1 July following your 31st birthday, you generally have 1,094 days from discharge to take out hospital cover at the base rate, before a Lifetime Health Cover loading applies. We can plan any health cover into your civilian budget.
Yes, and questions about super, cover, DVA payments and retirement can come up at any stage after service. Since 1 July 2026, all new compensation claims are decided under one set of rules, whenever you served.
We can bring your super, cover and any payments, including any closed scheme pension, into one plan, and work through any choice that has a time limit before that time runs out. If a claim is part of the picture, an ex-service organisation advocate can help you prepare it.
Your accountant and financial adviser bring different expertise to the same decisions. Your accountant can advise on tax reporting, structures and consequences; we help you plan how cashflow, debt, super, investments and protection work towards your goals. We can coordinate before important decisions.
What an accountant does
- Prepares and lodges tax returns, BAS and financial statements
- Advises on tax structures such as companies, trusts and partnerships
- Manages bookkeeping, payroll and ATO compliance
- Provides tax advice on the consequences of a transaction
What a financial adviser does
- Sets a long term strategy across retirement, investing and cash flow
- Builds wealth from early in a working life, starting with cash flow, a first home and super
- Recommends specific super funds, investments and personal insurance
- Operates under an Australian Financial Services Licence, which is required to give personal advice on financial products
- Handles retirement planning, Centrelink and aged care strategy, and estate planning considerations
Professional roles and authorisations matter. We provide financial advice within our authorisations and work with your accountant for specialist tax advice and lodgements.
Where they work together
- Tax position. Your accountant confirms your marginal rate, deductions and carried forward losses, which shapes decisions on super contributions, investment structures and the timing of asset sales.
- Business and entity structures. Your accountant advises on the structure itself and your financial adviser works within it for investments, insurance and succession planning.
- Cash flow. Your accountant’s figures can help us understand what’s available for debt repayment, protection and longer-term goals.
- Before key decisions. We can coordinate with your accountant on contributions, asset sales and other material choices in time to consider relevant tax consequences.
We’re a national service, so you can meet with us by phone or video from anywhere in Australia. We also have offices in three cities:
- Sydney: offices in Sydney CBD, Parramatta, Seven Hills, Ingleburn and Narellan, servicing areas including the City of Sydney, Eastern Suburbs, Inner West, North Shore, Northern Beaches, Sutherland Shire, Blacktown, Liverpool, Campbelltown and all surrounding suburbs.
- Melbourne: our St Kilda Road office, servicing areas including the City of Melbourne, Port Phillip, Boroondara, Monash, Casey, Wyndham and all surrounding suburbs.
- Brisbane: our Eagle Street office, servicing areas including Brisbane City, Moreton Bay, Ipswich, Logan, the Gold Coast, the Sunshine Coast and all surrounding suburbs.
Absolutely, and you can start wherever you are in the move out of service. Tell us your separation date if you have one, what’s changing and what you’d like help with first.
There’s no cost for the initial conversation. Any advice after that is a paid service, with its scope and fee agreed with you in writing first. We’ll explain how we can help and what we’d look at first. Useful documents include a separation or discharge letter, super statements, recent payslips and any letters from DVA or your fund.
Reviews
Testimonials from Our Clients
Client Success Stories
 A Property Sale Became a Full PlanEstimated long term financial benefitApprox $448,000
 A Plan to Keep the Family HomeLife cover established$1.2 Million
 Cover in Place and Fees LoweredImmediate value$1,055 a year
 Super Fees More than HalvedProjected retirement uplift$416k
 Income Covered for a New MortgageImmediate value$975 a year
 A 13-Year Mortgage Paydown PlanPlanned mortgage paydown13 years
 A First Home and Family CoveredImmediate value$1,346 a year
 Age Pension Kept After an InheritanceProjected uplift at 90More than $642,000
Grow & Protect Your Wealth Today
Whatever’s on your mind, we’re here to help. You’ll speak with an authorised financial adviser who’ll listen first and get to know what matters to you.
Book An Initial Conversation