
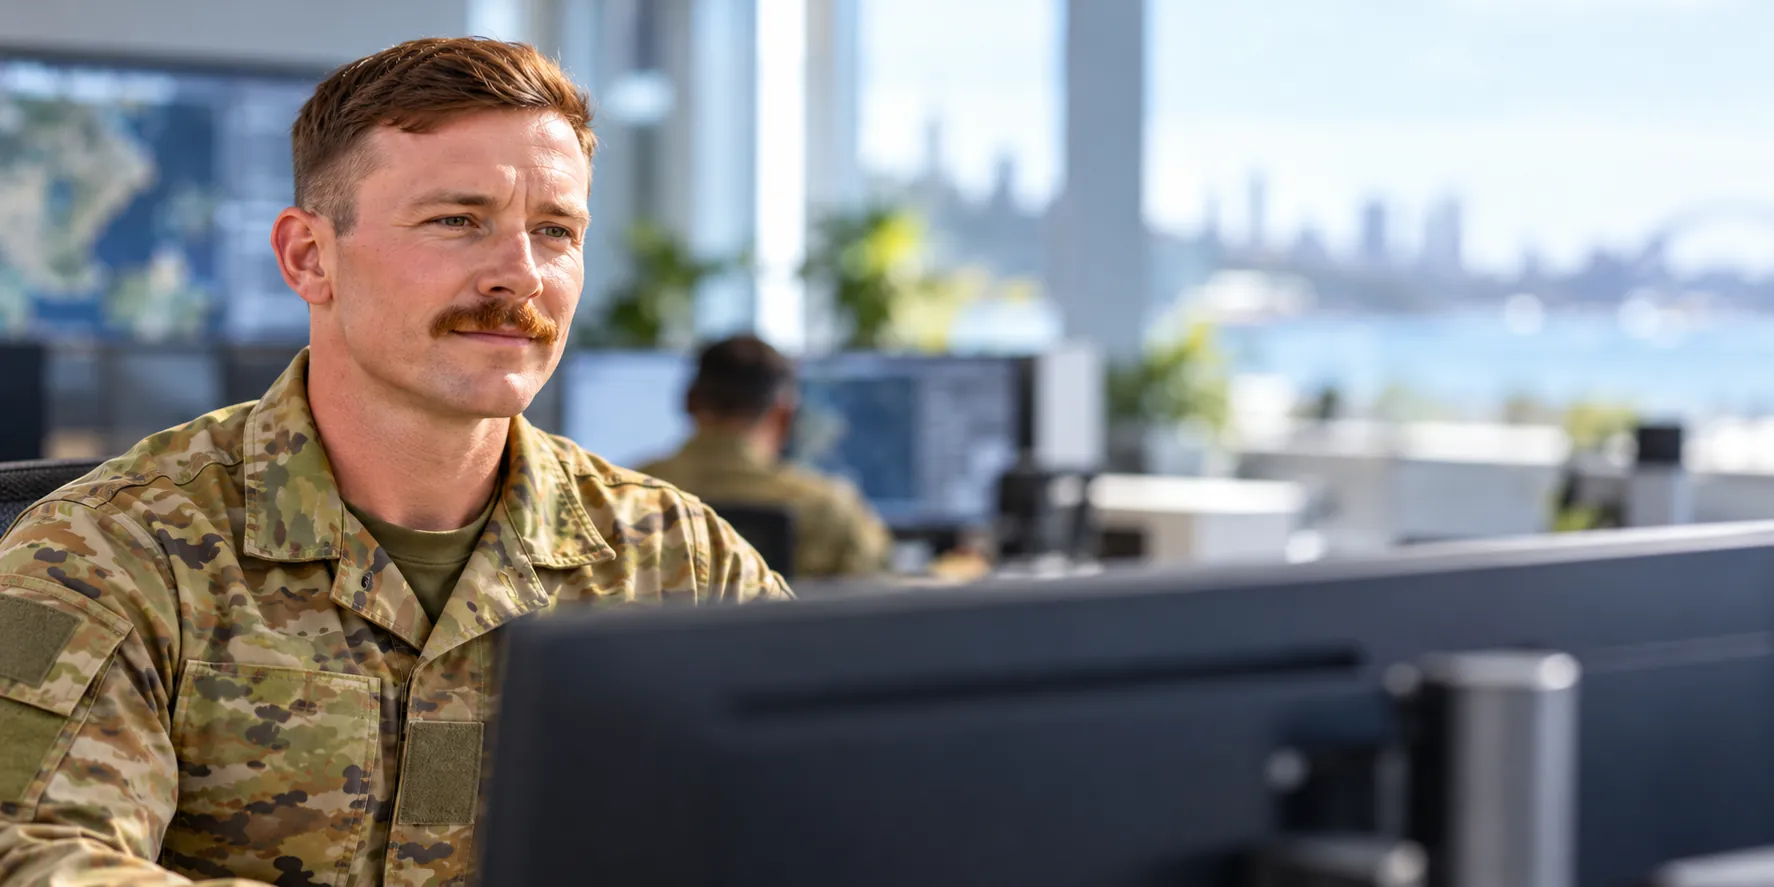
Financial Planning for Public Sector and Defence Employees
We Help Public Sector and Defence Personnel Build Prosperity and Freedom
Super scheme rules, allowances, postings and cover through your role can all affect the rest of your financial plan. We help you understand what your scheme provides and build the rest of your plan around it.
Our Financial Advice Team Is Here to Help You
We Can Help You
- Understand what a defined benefit scheme may be worth to you
- Review your member contribution rate, where your scheme allows a choice
- Compare a scheme pension with a lump sum, where both are offered
- Check what your scheme covers if something happens
- Consider any salary packaging your employer makes available
- Budget around shift work, allowances and postings
- Review super held outside the scheme and whether to consolidate
- Plan the move to civilian work and a new super fund
Who We Help
- ADF members moving with each new posting
- Reservists balancing service with a civilian career
- Police, fire and ambulance officers on shift work and penalty rates
- Teachers and educators with scheme rules worth understanding
- Public servants with super built over a long career
- Defence and service families moving house and school with each posting
- Members leaving the service deciding what to do with the benefit
- Members retiring early whose scheme may allow an earlier finish
What we advise on
How Our Advice Works for Public Sector and Defence Households
Superannuation
We’ll explain why a defined benefit is a formula rather than an account balance.
A defined benefit is generally worked out from a formula set by the scheme, which may draw on your years of service, a defined salary and your contribution rate. Each scheme sets its own terms, and several are closed to new members. We work through your scheme’s rules with you before considering any change.
Together, we’ll work through:
- Which scheme you are in, and whether it is a defined benefit or accumulation one
- The formula behind your benefit, and which inputs can change the amount
- Your member contribution rate, and what changing it does to the final benefit
- Why a defined benefit is not a balance you can compare against a fund
- What happens to the benefit if you leave the service before the usual date
- Any accumulation account sitting alongside the scheme, and how it is invested
- Whether extra contributions inside the scheme or outside it are more suitable for you
- How a value on your statement may differ from the benefit the scheme pays at exit
Financial Planning & Advice
We’ll help you plan one financial position across a career of postings and transfers.
A service career can mean a home in one city, a posting in another and a partner’s career that moves with yours. We bring housing, super, cover and household income into one plan, so each move can be considered alongside the others, and we revisit it as postings change.
Together, we’ll work through:
- One financial position held across a career of postings and transfers
- How postings may affect a partner’s career and income over time
- Housing decisions when the next posting is unknown, buying against renting
- What the scheme covers, so the rest of the plan is built around it
- How a transition out of service may change income, super, cover and housing together
- Records kept in a form that survives moving house every few years
- What can be arranged remotely, given where you might be posted next
- What gets reassessed at each posting, and what carries across unchanged
Property Investment Advice
We can help you plan property decisions around a posting cycle and the moves it brings.
Buying where you’re posted isn’t always practical, and renting throughout has its own costs. Some members keep a home and rent it out while serving elsewhere. The main residence rules that may apply carry conditions and time limits, so we work through them with you and your accountant before the first move.
Together, we’ll work through:
- Buying where you can afford while renting where you’re posted, and whether the arrangement suits your plan
- The six-year main residence rule for a home you rent out, checked with your accountant
- How moving back into the home may reset that six-year period, confirmed with your accountant
- Stamp duty and other transaction costs that may arise if you buy and sell with each posting
- Living in a service residence while a home of your own sits let elsewhere
- Whether an investment suits a career that relocates you every few years
- How lenders may treat allowances, a question to work through with your broker
- A property chosen for a tenant market rather than for where you happen to be
Personal Insurance & Protection
We’ll show you what your scheme covers for death and invalidity, and where it stops.
Public sector and defence schemes may include invalidity or death benefits, with definitions set by the scheme. Cover held outside the scheme is assessed separately, and insurers may treat operational or high-risk duties differently, including through exclusions or higher premiums. We check what you already hold before recommending more.
Together, we’ll work through:
- What your scheme covers for death and invalidity, and where that stops
- Any classification categories, and what each one may pay under your scheme’s rules
- Whether retail cover is needed at all, or only to fill a specific gap
- How service-related exclusions work on cover bought outside the scheme
- What changes to the cover on the day you leave the service
- Whether a retail policy’s terms would cover a claim arising during a deployment
- How any income protection in your scheme works alongside sick leave, and the conditions attached
- Scheme and default cover listed first, so any new policy fills a real gap rather than repeating one
Retirement & Aged Care
We’ll help you plan for your finishing age, including whether your scheme allows an earlier one.
Finishing work earlier can mean your savings have more years to cover. Where a scheme offers a choice between a pension and a lump sum, the decision may not be reversible, and it can depend on your health, your partner, your other assets and what the money needs to do.
Together, we’ll work through:
- An earlier finishing age, if your scheme allows it, and the longer retirement it may mean
- Whether to take the benefit as a pension or as a lump sum
- How a lifetime pension compares with control over a lump sum, under your scheme’s terms
- What a second career after service does to the plan and to the tax
- How Centrelink treats a defined benefit pension under the income test
- Whether the scheme benefit alone could support the lifestyle you want after work
- Whether a pension would continue to your spouse after you die, under your scheme’s rules
- A projection that allows for finishing work earlier, if your scheme permits it
Cashflow & Financial Wellbeing
Together, we can build a budget on base pay when allowances move with the posting.
Where part of your income comes from allowances tied to where you are and what you’re doing, it can help to plan household commitments around base pay. Housing assistance and relocation costs can also change with each posting, so we look at the timing of each.
Together, we’ll work through:
- Budgeting on base pay, with allowances treated as a separate layer
- What each allowance is tied to, and the point at which it would stop
- Any housing assistance, and the cost of accommodation on each posting
- What a posting overseas does to income, to costs and to everything between
- A buffer for the period between postings, with a realistic plan for building it
- Which commitments can be paused if a posting changes at short notice
- Where the allowance layer is directed, decided before it arrives
- How changes in a partner’s income may affect the household budget
Tax & Wealth Strategies
We’ll walk you through salary packaging in a public role, and the cap that applies to it.
Some public sector and not-for-profit employers can offer salary packaging with fringe benefits concessions, up to a cap that depends on the employer type. Packaging can also affect the income figure used in other assessments, such as family payments. We work with your accountant on the tax details.
Together, we’ll work through:
- Salary packaging in a public role, and the cap that applies to your employer
- Which items may be exempt, and how the grossed-up cap applies to your employer
- How allowances are taxed, and whether any are exempt during a deployment, with your accountant
- Possible work-related deductions, and the records your accountant may need for each
- The components of a scheme lump sum, and the tax treatment of each
- Allowances and tax residency during an overseas posting, with your accountant’s advice on each
- Whether an investment property still suits a career that moves this often
- What your tax agent needs each year, given the paperwork moves with you
SMSF
We’ll tell you what a self-managed fund can and can’t do alongside a defined benefit.
A defined benefit interest generally can’t be moved into a self-managed fund, so a fund would sit alongside it rather than replace it. An SMSF also brings costs, administration and legal responsibilities as a trustee, and residency rules can matter if you’re posted overseas. We consider whether it suits you before any change.
Together, we’ll work through:
- What a self-managed fund can and cannot do alongside a defined benefit
- Why a defined benefit interest generally cannot be moved into one
- Whether any accumulation account beside the scheme is large enough to justify a fund
- The running costs against a balance that sits mostly inside the scheme
- How the fund would be administered through a posting or a deployment
- The trustee obligations, and who would meet them while you are away
- An overseas posting and its possible effect on an SMSF’s residency, considered before the fund is set up
- Whether the interest is really investment control, or simply more visibility
What We’ll Work Through Together
What Your Defined Benefit Is Worth
Understand how your scheme’s formula works and what it may provide.
Your Scheme Contribution Rate
Review whether your contribution rate still suits you, where the scheme allows a choice.
Pension or Lump Sum
Compare both options where offered, since the choice may not be reversible.
Invalidity and Death Cover
Understand what your scheme may provide and the definitions that apply.
Salary Packaging in the Public Sector
Consider packaging options and the cap that applies to your employer type.
Budgeting Around Postings
Plan household spending around base pay as allowances change with postings.
Leaving the Service
Review your benefit, cover and super access before you leave.
Planning an Earlier Retirement
Plan for the extra years an earlier finish may need to fund.
Proactive, Holistic, and Experienced Financial Planning
Serving in uniform or in the public sector can come with super arrangements that work differently from an ordinary fund, including a defined benefit scheme for some members. Where you have one, it can be valuable, and it’s worth understanding how it works. We’ll help you see what your scheme provides in plain terms, and how the rest of your plan could be built around it, so your savings and cover are working towards the life you want after service.
These careers can come with postings, deployments and a partner whose own career moves around yours. All of it can affect what’s possible and when. We’ll take the whole household into account rather than only the scheme, and we can review the plan with you as postings and circumstances change. We can help you plan for the years after service, towards a life that suits you, whatever it turns out to look like.
Every financial decision impacts the next
Your Financial Life Is Connected
Great advice starts with understanding the bigger picture. Every stage of life presents new opportunities and challenges, from buying property and changing careers to growing your family, planning for retirement and protecting what matters most. At Ryker, we help connect every piece of your financial world into one clear strategy.
Your
Wealth
- Property & Investing
- Career & Income
- Tax Strategy
- Insurance & Protecting Your Family
- Super & SMSF
- Wealth & Investments
- Life Events & Changes
- Business & Wealth
- Legacy & Future Wealth
- Retirement Planning
Frequently Asked Questions
We’re invested in your long-term success. What we do is personal, and we take it personally.
Your financial decisions connect, so we consider the parts of your financial life that are relevant to the advice you need:
- Property & Investing
- Career & Income
- Tax Strategy
- Insurance & Protecting Your Family
- Super & SMSF
- Wealth & Investments
- Life Events & Changes
- Business & Wealth
- Legacy & Future Wealth
- Retirement Planning
This is how we help you make decisions today with your longer-term goals in view.
Everybody’s situation is different, so we listen first, understand what matters to you and explain your options clearly before we make a recommendation.
Start with your scheme’s formula rather than a balance.
Many defined benefit schemes calculate a benefit from a formula that may draw on your years of service, a salary figure the scheme defines and your own contribution rate. The amount on a statement may not show everything that affects the final benefit.
Your contribution rate, the salary definition your scheme uses and whether the benefit is taken as a pension or a lump sum can all change the answer. We work through your scheme’s own rules rather than generalising about schemes.
A financial adviser can give personal advice that considers your whole position, while a scheme helpline can explain its own rules, and it’s worth using for that.
Helplines may provide information rather than personal advice, and they may not consider everything else you own. We can look at whether a pension or lump sum suits you, what your cover would provide for your family, and how a posting or a partner’s income may change the plan.
Financial advisers must meet education and exam requirements, complete ongoing professional development, be registered, and act in your interests.
It depends on your scheme and your circumstances, and it can be one of the largest decisions you make, which may not be reversible. Factors to weigh include:
- A pension can provide regular income for life, often indexed, depending on the scheme.
- A lump sum offers flexibility and control, along with investment risk.
- The tax treatment differs, and it varies by scheme and by age.
- Centrelink treats the two differently, which can change an entitlement.
Your health, your partner’s position and everything else you own can all affect the answer, so we model the options with you before you decide.
Your accountant and financial adviser bring different expertise to the same decisions. Your accountant can advise on tax reporting, structures and consequences; we help you plan how cashflow, debt, super, investments and protection work towards your goals. We can coordinate before important decisions.
What an accountant does
- Prepares and lodges tax returns, BAS and financial statements
- Advises on tax structures such as companies, trusts and partnerships
- Manages bookkeeping, payroll and ATO compliance
- Provides tax advice on the consequences of a transaction
What a financial adviser does
- Sets a long term strategy across retirement, investing and cash flow
- Builds wealth from early in a working life, starting with cash flow, a first home and super
- Recommends specific super funds, investments and personal insurance
- Operates under an Australian Financial Services Licence, which is required to give personal advice on financial products
- Handles retirement planning, Centrelink and aged care strategy, and estate planning considerations
Professional roles and authorisations matter. We provide financial advice within our authorisations and work with your accountant for specialist tax advice and lodgements.
Where they work together
- Tax position. Your accountant confirms your marginal rate, deductions and carried forward losses, which shapes decisions on super contributions, investment structures and the timing of asset sales.
- Business and entity structures. Your accountant advises on the structure itself and your financial adviser works within it for investments, insurance and succession planning.
- Cash flow. Your accountant’s figures can help us understand what’s available for debt repayment, protection and longer-term goals.
- Before key decisions. We can coordinate with your accountant on contributions, asset sales and other material choices in time to consider relevant tax consequences.
Consider setting household commitments around base pay, and treating allowances as a separate, changeable layer.
Allowances attach to where you are and what you’re doing, and they can stop when a posting ends. If the mortgage and fixed costs sit on base pay, a change of posting may be easier to manage.
It can also help to decide in advance what any allowance income is for, such as a buffer, an offset account if your loan has one, super or a specific goal. We can help you plan that before the next posting.
For an accumulation account, comparing funds online can be a reasonable starting point, and comparison tools can show fees and past returns.
A defined benefit works differently. It isn’t an account balance, it doesn’t have a return in the usual sense, and leaving a scheme may not be reversible.
You can compare any accumulation accounts you hold alongside it. Before making a decision about the scheme itself, it’s worth getting advice. We can look at how your scheme and other super fit together in your circumstances.
It depends on your scheme, and the definitions are set by the scheme rather than by the retail insurance market.
Public sector and defence schemes may include invalidity and death benefits, sometimes paid as a pension rather than a lump sum, and the criteria for classification can be specific.
The two things to establish are what may be paid and where the scheme’s cover stops. Any retail cover can then be considered against that gap, so you’re less likely to pay for cover you already hold.
Start with the decisions that may carry a deadline. An order worth considering, depending on your circumstances:
- What happens to your scheme benefit, and whether any decision carries a deadline.
- What cover may end with the role, and whether anything should be in place before it does.
- What your income may look like in the first year out, including any transition payments, with the tax checked with your accountant.
- Whether your super arrangements change with a new employer.
Cover can be time-sensitive, because some options may only be available while you’re still serving, and new cover is assessed on your health when you apply.
Very much so. Tell us which scheme you’re in, roughly how long you’ve been contributing and what you’d like the years after service to look like, and we can start there.
There’s no cost for the initial conversation. We’ll explain how we can help and what will help us get started, such as your latest scheme statement and details of any cover you hold.
Understanding your scheme first gives the rest of the plan a clear starting point.
Who We Help
Advice for All Stages of Life
From first job to retirement, we help you build wealth, protect it, and live well.
Starting Out
First jobs, first home, first super, HECS debt, budgeting and more.
Growing Families
First home buyers, new parents, school fees, single incomes, young families and more.
Medical & Health
Doctors, dentists, pharmacists, allied health, nurses and more.
Professional Services & Tech
Lawyers, accountants, brokers, engineers, consultants and more.
Trades & Business Owners
Electricians, plumbers, builders, sole traders, franchisees and more.
Corporate & Executive
Executives, senior managers, directors, board members and more.
Public Sector & Defence
Police, firefighters, paramedics, ADF personnel, teachers and more.
Approaching Retirement
Pre-retirees, transition to retirement, Age Pension, aged care, estate planning and more.
Other Stages
Any income, any stage, career changers, separation, second opinions and more.
Reviews
Testimonials from Our Clients

Grow & Protect Your Wealth Today
Whatever’s on your mind, we’re here to help. You’ll speak with an authorised financial adviser who’ll listen first and get to know what matters to you.
Book An Initial Conversation