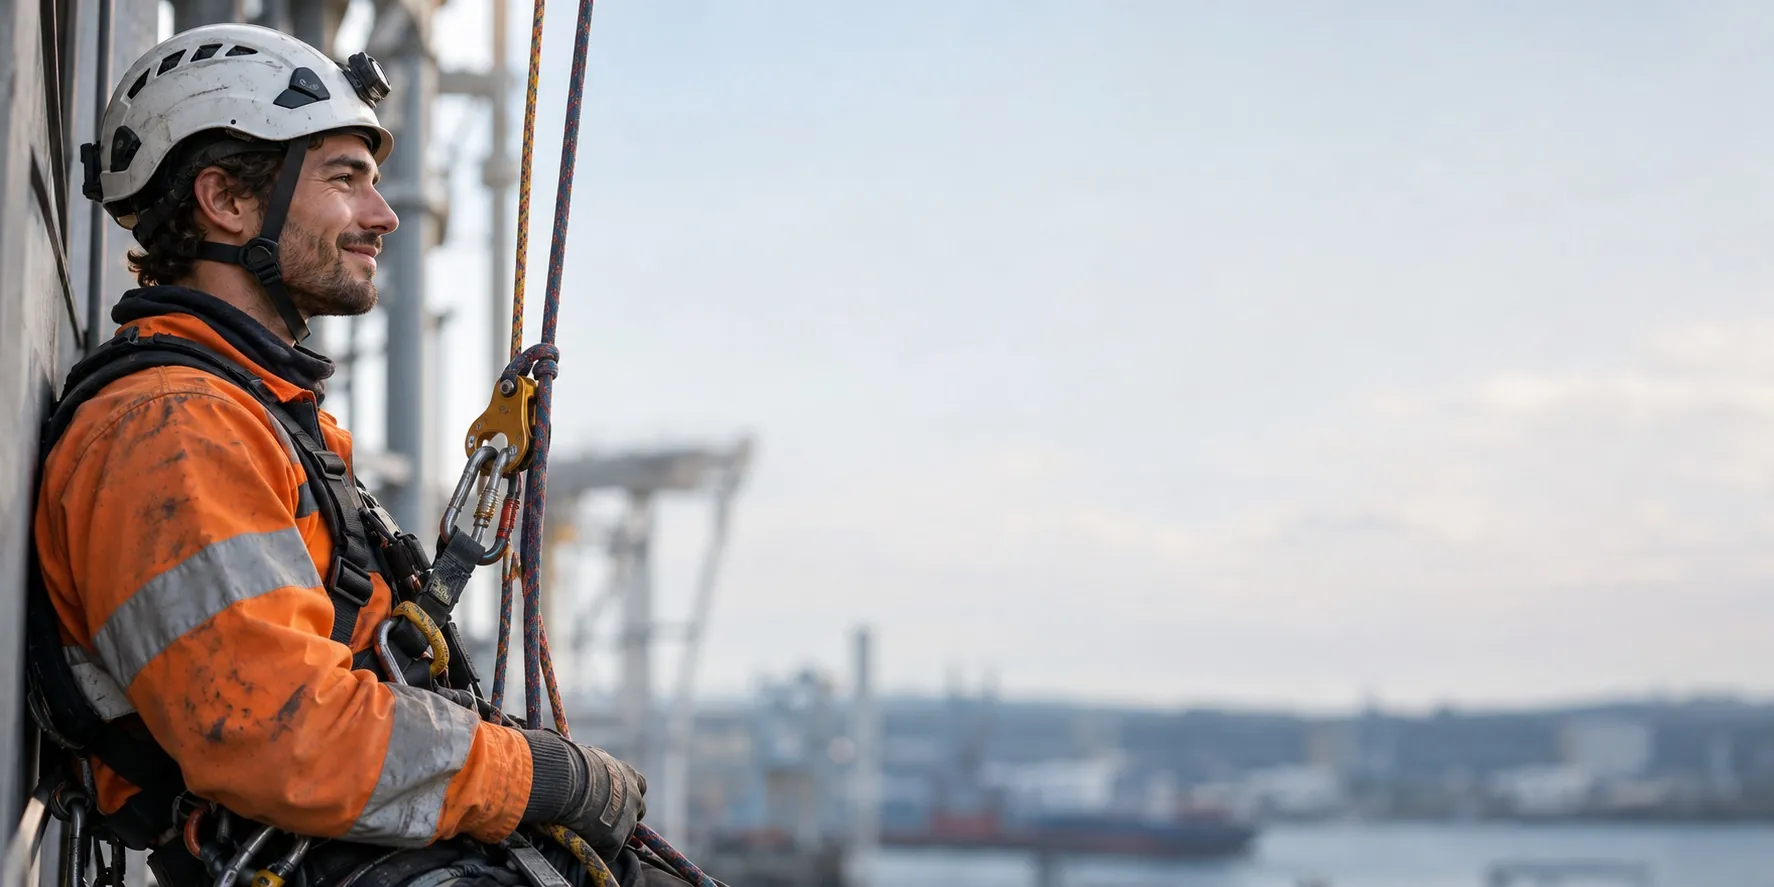
Financial Planning for Rope Access Workers
Financial Advice Empowering Rope Access Workers to Build Wealth and Freedom
Your rope access work, pay that can change between campaigns, any tickets you hold and your plans outside work all connect. We can help you bring them into one plan, from a first job on ropes to supervising.
Our Financial Advice Team Is Here to Help You
Who We Help
- Technicians new to rope access fresh from a first course
- Blasters and painters doing their trade on ropes
- Welders and other trades adding rope access to what they do
- Inspection and testing technicians reaching the work by rope
- Building maintenance techs including facade and window work on ropes
- Casual and campaign crews on shutdowns or remote work
- Level 3s and supervisors looking after rope access teams
- Small rope access businesses and the people who own them
We Can Help You
- Explain what each cover does, then compare options with you from the insurers willing to consider your work
- Build a budget from a full year of rope access income, including time between campaigns
- Set a share of long campaign pay aside in your budget for goals you choose
- Follow your super across rope access employers, with who pays on any ABN work confirmed by an accountant or the ATO
- Plan the tax on income that varies between campaigns, alongside an accountant
- Allow for the time and cost of re-certifying any tickets you hold in your budget
- Cost a step into supervising, inspecting or training, with pay and duties in your financial plan
- Plan a retirement on super and savings, with a year in mind for leaving rope work
What we advise on
How Our Advice Works for Rope Access Workers
Personal Insurance & Protection
How could money keep coming in if illness or injury meant time away from rope access work?
Income protection can pay a share of income after a waiting period, subject to its terms, exclusions and the insurer’s assessment.
We’ll weigh up life, TPD and income protection with you from the insurers willing to consider your work.
An insurer usually looks at your job and duties when you apply, and this can affect whether cover is offered, the benefit periods available and the amount. Exclusions can apply, including to occupations or activities. Income protection usually pays a share of your pre-tax income if illness or injury stops you working, based on your earnings in the 12 months before, and most policies offer a waiting period between 14 days and two years. The insurer decides on any application.
Together, we’ll work through:
- What you do on ropes, from inspecting to blasting or welding, answered with reasonable care on an application
- Casual rope work with no paid sick leave, and the wait your savings could handle before a policy could pay
- Minimum hours, if a policy sets them, read against the weeks between rope access campaigns
- Cover that comes through a job or fund, if you have some, read for its amount and how long it lasts
- Inspection or supervising experience, and how TPD any occupation wording may count what you’ve learned on ropes
- Life and TPD sums sized with a home loan in mind, if you have one, and what your rope work pays for
- An ABN offer for a rope job, with questions about income protection and insurance in super raised before you accept
- A move away from rope work, and what to read in your cover, if you hold some, before that change
Learn more about Life Insurance and Income Protection for Rope Access Workers
Cashflow & Financial Wellbeing
Across a year of rope access work, what would you like your income to pay for?
Planning from a full year’s income can set aside part of each good stretch for bills, savings and goals of your own.
We can build a budget with you from what a year of rope access work brings in, not one campaign’s rate.
Rope access jobs can be casual, permanent or on contract, and some add allowances or run on a roster. An hourly rate shows what a week can pay, while a year of payslips or invoices also shows any time between jobs. We start from that yearly figure, then plan a buffer, your bills and your own goals around it.
Together, we’ll work through:
- Last year’s payslips or invoices used as the starting point, rather than the hourly rate on a campaign offer
- Day or night rates, and any allowance, counted at what they paid you instead of assumed for every week
- A share of a long campaign’s pay sent to a buffer before it goes on everyday costs
- Money for weeks between campaigns, if your work has gaps, worked out from last year and set aside from strong stretches
- Any remote rope jobs, with time away, flights, meals or accommodation you pay for counted separately
- Time off for re-certifying, if you hold IRATA tickets, planned into your budget with any cost it brings
- Household goals such as a home, a holiday or time with family, given a set amount from your rope access pay
- Weekly or fortnightly pay from different employers, brought together into one budget for the whole year
Superannuation
Once each employer’s payments are traced, what could your rope access super look like?
Seeing what each employer has paid can show where your super sits and what you’d like to add.
We can trace your super with you across rope access employers, short campaigns and any ABN work.
On a contract, a business may still have to pay super if you’re paid mainly for your labour. The ATO looks at whether more than half the contract’s value is for your labour, whether payment depends on a set result and whether the work can be delegated, and an ABN doesn’t settle it. The hirer doesn’t have to pay under a contract with your own company, trust or partnership. An accountant or the ATO can confirm where you stand.
Together, we’ll work through:
- Payslips from every rope access employer, set beside your fund statements to show what each one paid
- Any extra funds opened for short campaigns, each one listed with its fees and insurance
- Changing rope access employers, and why your existing fund generally keeps receiving super unless you pick another
- Extra super from a long rope access campaign, kept within a cap that’s indexed and can change
- A rope job on an ABN, and the ATO’s tests taken together: mainly labour, no set result, no delegating
- A rope access contract signed by a company, trust or partnership you run, and why the ATO says that hirer has no super to pay
- Insurance in a fund, if there’s some, with premiums coming off the super you’ve built on rope jobs
- Any funds from earlier campaigns brought together, only after you’ve read the insurance in each
Tax & Wealth Strategies
When your income changes between campaigns, which tax decisions are worth planning ahead?
Estimating tax with an accountant during the year can leave fewer surprises when your income has moved around.
We’ll map the tax side of varying rope access income with you, alongside an accountant.
Ryker’s financial advisers plan tax and set tax structure and strategy, working alongside your accountant, who prepares and lodges your return. Income that changes through the year can change what you owe, and an accountant can estimate the amount. What you can claim for gear, tickets and travel is also a question for an accountant.
Together, we’ll work through:
- Tax estimates in a year when campaigns start and stop, worked through with an accountant
- Whether harness, gear, ticket and travel costs can be claimed, as a question for an accountant
- A set-aside for tax on each rope access invoice, if you’re on an ABN, with an accountant estimating it
- A personal super contribution you’d like to deduct, and the notice your fund needs, confirmed with an accountant
- Structure for a growing rope access business, and whether a company or trust would suit, with an accountant
- Room in your budget for PAYG instalments between campaigns, if the ATO sets these for you
- Rope job payslips and invoices stored together, ready for an accountant doing your return
- A buyer for a rope access business, if you own one, with an accountant advising on any small business CGT concessions retained after 1 July 2027
Financial Planning & Advice
From your first rope ticket to supervising, which move would you like to plan next?
Costing a move ahead of time can show the pay, the time it takes and what changes outside work.
Together, we’ll cost your next move in rope access work and set it out in a financial plan, or Statement of Advice.
Under IRATA, technicians may progress through three levels as time, experience and training allow, and each technician re-certifies every three years. A move up, or into supervising, inspecting or training, can change your duties, your hours and the way you’re paid. We plan the money side with you, and any question about a ticket goes to the body that issues it.
Together, we’ll work through:
- Going from Level 1 to Level 2 or 3, with the training time, anything you’d pay yourself and any change in pay
- Adding a trade or inspection qualification, and what study and time off could mean for your budget
- Local building work compared with remote campaigns, including what each could mean for your income and your week
- A casual rope access role turning permanent, weighed for leave, pay and how you’d budget
- An ABN offer or a small business of your own, with leave and super looked at first
- Supervising, inspecting or training as your next role, and what the pay could do for your goals
- More time off, a home or a family, weighed up alongside the rope access work you’d like to be doing
- A yearly look at your rope access plan and the goals you’ve set, through ongoing advice
Retirement & Aged Care
After your years of rope work, how would you like to spend your time?
Looking ahead can give you more choice over when you stop rope work and what comes after.
We’ll shape your retirement plan with you on super and savings first, then any later stage of work.
A plan can start with when you’d like to stop rope work, and whether supervising, inspecting or training could come first. Super and savings can then form the base of your retirement income. Preservation age is 60 for anyone born from 1 July 1964, and super can generally only be accessed once you meet a condition of release, such as ceasing employment at 60 or over.
Together, we’ll work through:
- Your preferred year for leaving rope work, with the income you’d want from then on beside it
- Time supervising, inspecting or training before you stop, with the pay and any extra super from the role
- Fewer campaigns as you wind back, and how your budget could change with lower income
- Your own contributions in your final years of rope access work, within a cap that’s indexed
- Any accounts from earlier jobs, weighed up for fees and insurance before one is closed
- A buyer for your rope access business, if you own one, treated as an extra rather than the base
- Drawing an income from super after a condition of release, at a yearly amount that suits your plans and any minimum that applies
- Stopping rope work at the same time as a partner, if you have one, and how your super lines up
Property Investment Advice
Through a slow stretch between campaigns, would a home or investment still fit your budget?
Running the repayments through a quiet stretch of work can show how a purchase could sit in your budget.
We’ll test a purchase with you against a slow stretch of rope access work, and a broker arranges any loan.
A lender decides how it reads casual, campaign or ABN income, and a broker compares lenders and arranges any loan. Borrowing to invest can magnify losses as well as gains, and the loan must still be repaid if values fall. From 1 July 2027, negative gearing on residential property is limited to new builds, though property held on 12 May 2026 is exempt. New CGT rules generally apply to gains accruing after 1 July 2027.
Together, we’ll work through:
- Casual or campaign pay and how lenders read it, worth talking through with a broker first
- Buying while you’re away on a remote campaign, with a broker and a solicitor on the paperwork and timing
- Long campaign pay saved after tax towards a deposit, in an account of its own
- Repayments tested against your income in a year with long gaps between rope access campaigns
- Borrowing to invest on campaign income, and what you’d still owe if values fell
- Established or newly built investments, given the limit on negative gearing for residential property from 1 July 2027
- Any CGT when an investment sells, which is a question for an accountant
- Money kept aside after settlement, for months when rope access campaigns are further apart
Your Rope Access Finances, Worked Through Together
Cover Options for Rope Access Work
Options from the insurers willing to consider your work, talked through with you, with the insurer deciding any application.
A Budget Across Campaigns
A full year of rope access income set out in one budget, including any time between jobs.
Good Stretches Given a Purpose
A share of long campaign pay planned with you before it arrives.
Super Traced Across Employers
Payslips and fund statements from each rope access employer read together with you.
Casual Pay Planned
Casual pay and the paid leave it doesn’t bring, planned into your savings with you.
Tax on Varying Income Planned
Tax on income that changes through the year planned with you, alongside an accountant.
A Move to Supervising Costed
Pay, training time and duties weighed with you before you step into supervising, inspecting or training.
Retirement Beyond the Ropes
A retirement plan built on super and savings, with any later stage of work as an addition.
This has really changed our lives
Ray and his team has been incredible, they look after my entire family including my brother in law. Over the years he has helped us with investments, tax and other advice. This has really changed our lives.
Read moreDean Desoukey is changing lives!!
From the very beginning he was warm, patient, incredibly knowledgeable, and genuinely cared about helping us make the right decisions for our future. The positive impact they've had on our family financially and the peace of mind he's given us has been huge.
Read moreI felt heard, understood, and respected
I can't speak highly enough of the service I received from Dean Desoukey. Financial conversations can often feel overwhelming, but he created a space where I felt heard, understood, and respected. He took the time to really listen, explained things clearly, and never rushed me through decisions.
Read moreKnowledgeable, patient and caring
I cannot recommend Ray highly enough. He is an exceptional financial adviser: knowledgeable, patient and caring. From the very beginning, he took the time to truly understand my goals and helped me to create a clear structured financial plan. I never feel rushed or pressured.
Read moreThank you Ray for protecting me and my family
Ray has been my trusted financial adviser for over 12 years. He is highly knowledgeable and passionate about making sure his customers have the right insurance to secure them and their family. I was recently sick and Ray was there right away when needed most.
Read moreHe went above and beyond
I recently dealt with Ricky Regmi at Ryker Capital, and I couldn't be more satisfied with the service I received. Ricky was incredibly patient and supportive throughout the entire insurance process. He went above and beyond, coordinating with my accountant and doctor to ensure everything was in order.
Read moreIt never feels transactional
We've been working with Jack for the past two years, and it's been an incredibly positive experience. He takes the time to build genuine relationships and really gets to know his clients beyond just the numbers. It never feels transactional; it feels like he truly cares about our wellbeing.
Read moreImmensely professional and diligent
Ray has been immensely professional and diligent in my most recent SMSF restructure and insurance review. He not only tweaked it to make it work more for me and my future goals but recommended future strategies to help build my wealth. Cannot recommend him enough.
Read moreHolistic and Experienced Financial Advisers for Rope Access Workers
Rope access work takes training, skill and real care. Buildings, facades and industrial plants stay in good repair because of work like yours, and much of it is never seen from the ground. We begin by listening: how your work runs from one job to the next, what you care about and what you’d like more of. Then we can shape a plan with you that suits your income and your life outside work.
A good stretch of work can do more than pay this month’s bills. It could go towards a home, a family holiday, time off you’ve chosen to take or a rope access business of your own one day. If someone depends on your pay, they can be part of the plan too. Whatever matters most to you, we can review the plan with you each year through ongoing advice, with those goals in view.
Every financial decision impacts the next
Your Financial Life Is Connected
Great advice starts with understanding the bigger picture. Every stage of life presents new opportunities and challenges, from buying property and changing careers to growing your family, planning for retirement and protecting what matters most. At Ryker, we help connect every piece of your financial world into one clear strategy.
Your
Wealth
- Property & Investing
- Career & Income
- Tax Strategy
- Insurance & Protecting Your Family
- Super & SMSF
- Wealth & Investments
- Life Events & Changes
- Business & Wealth
- Legacy & Future Wealth
- Retirement Planning
Frequently Asked Questions
We’re invested in your long-term success. What we do is personal, and we take it personally.
Your financial decisions connect, so we consider the parts of your financial life that are relevant to the advice you need:
- Property & Investing
- Career & Income
- Tax Strategy
- Insurance & Protecting Your Family
- Super & SMSF
- Wealth & Investments
- Life Events & Changes
- Business & Wealth
- Legacy & Future Wealth
- Retirement Planning
This is how we help you make decisions today with your longer-term goals in view.
Everybody’s situation is different, so we listen first, understand what matters to you and explain your options clearly before we make a recommendation.
Start from what you earned across a full year, taken from your payslips or invoices, rather than the rate on one campaign. That figure takes in any weeks between jobs.
From there, a budget can set out:
- Regular bills and repayments, on the income you can rely on
- A buffer for the time between campaigns
- A share of long campaigns for savings, super or a goal of your own
If rope access is new to you, a cautious estimate can stand in until you have a year of figures. We can work through it with you from your own numbers.
Your accountant and financial adviser bring different expertise to the same decisions. Your accountant can advise on tax reporting, structures and consequences; we help you plan how cashflow, debt, super, investments and protection work towards your goals. We can coordinate before important decisions.
What an accountant does
- Prepares and lodges tax returns, BAS and financial statements
- Advises on tax structures such as companies, trusts and partnerships
- Manages bookkeeping, payroll and ATO compliance
- Provides tax advice on the consequences of a transaction
What a financial adviser does
- Sets a long term strategy across retirement, investing and cash flow
- Builds wealth from early in a working life, starting with cash flow, a first home and super
- Recommends specific super funds, investments and personal insurance
- Operates under an Australian Financial Services Licence, which is required to give personal advice on financial products
- Handles retirement planning, Centrelink and aged care strategy, and estate planning considerations
Professional roles and authorisations matter. We provide financial advice within our authorisations and work with your accountant for specialist tax advice and lodgements.
Where they work together
- Tax position. Your accountant confirms your marginal rate, deductions and carried forward losses, which shapes decisions on super contributions, investment structures and the timing of asset sales.
- Business and entity structures. Your accountant advises on the structure itself and your financial adviser works within it for investments, insurance and succession planning.
- Cash flow. Your accountant’s figures can help us understand what’s available for debt repayment, protection and longer-term goals.
- Before key decisions. We can coordinate with your accountant on contributions, asset sales and other material choices in time to consider relevant tax consequences.
That depends on your employer’s industry and your duties, rather than your job title. Two people on one job can sit differently if they work for different employers.
Fair Work is the place to check which award or agreement applies to you, including where the national award system applies, and it helps to have your employer’s details and a list of your duties ready. Whatever you find, we can build your plan with you from your payslips.
Fair Work says casuals don’t get most types of paid leave, notice of termination or redundancy pay, even if they work regularly for a long time. Points to plan:
- A buffer for time off and any weeks between jobs
- How long you could wait for a benefit, if you hold or apply for income protection, which is generally for illness or injury rather than losing a job
- The super each employer pays, read from your payslips
We can set this out with you and look at options from the insurers willing to consider your work, with the insurer deciding any application.
First, an ABN doesn’t settle who pays your super. A business may still have to pay it if more than half the contract’s value is for your labour, payment doesn’t depend on a set result and the work can’t be delegated. A contract with your own company, trust or partnership is different, as the hirer doesn’t have to pay. An accountant or the ATO can confirm where you stand.
It’s then worth looking at paid sick leave, which self-employed people don’t have, your income records from the first invoice, and workers compensation, where each scheme sets who qualifies. We can compare the offer with you against your current pay.
Begin with how the pay compares, including any change in hours, allowances or time away, using your last year of payslips or invoices. It’s then worth looking at:
- The training time and any cost, with questions about a ticket going to the body that issues it
- What you’d rely on each week in the new role, as the base of your budget
- Any cover you hold: the job on record, and how a definition may read your new duties
- Your new duties set out on any new application
We can go through it with you before you accept.
That depends on how you’re paid and what you hold. It could come from:
- Sick leave, if you’re entitled to it and have some
- Workers compensation, through a state, territory or Commonwealth scheme, and each scheme sets who qualifies
- Income protection, if you hold it, which can pay part of your income after a waiting period, subject to the policy’s terms and exclusions and the insurer’s assessment
- Savings, for any time in between
We can plan with you how these could fit together. The insurer decides any claim on a policy, and each scheme’s rules set who decides a workers compensation claim.
Start with a simple budget and your super, before the first campaign’s pay lands. It’s worth looking at:
- Which fund your super goes to, shown on your payslip
- Insurance in that fund: if you’re under 25, cover in a new fund may need asking for, depending on your job and your fund
- A small buffer of your own for any time between jobs
- The date your ticket needs renewing, if it has one, and what it could cost in time and money
We can set this up with you from your first payslips.
Yes. We can plan with you around when you’d like to finish rope work, whether you’d supervise, inspect or train first, and how a budget changes as campaigns wind down.
The plan would rest on super and savings, with the sale of any small rope access business as an addition. You can read more about our retirement advice.
We’re a national service, so you can meet with us by phone or video from anywhere in Australia. We also have offices in three cities:
- Sydney: offices in Sydney CBD, Parramatta, Seven Hills, Ingleburn and Narellan, servicing areas including the City of Sydney, Eastern Suburbs, Inner West, North Shore, Northern Beaches, Sutherland Shire, Blacktown, Liverpool, Campbelltown and all surrounding suburbs.
- Melbourne: our St Kilda Road office, servicing areas including the City of Melbourne, Port Phillip, Boroondara, Monash, Casey, Wyndham and all surrounding suburbs.
- Brisbane: our Eagle Street office, servicing areas including Brisbane City, Moreton Bay, Ipswich, Logan, the Gold Coast, the Sunshine Coast and all surrounding suburbs.
Yes. Wherever you’re starting from, we can start there too, from a first rope access course to a casual campaign or your own small business.
There’s no cost for the initial conversation. Any advice after that is a paid service, with its scope and fee agreed with you in writing first.
It’s useful to have your recent pay records, your latest super statement and any policy documents with you. We can meet in person or online.
Reviews
Testimonials from Our Clients
Client Success Stories
 A Property Sale Became a Full PlanEstimated long term financial benefitApprox $448,000
 A Plan to Keep the Family HomeLife cover established$1.2 Million
 Cover in Place and Fees LoweredImmediate value$1,055 a year
 Super Fees More than HalvedProjected retirement uplift$416k
 Income Covered for a New MortgageImmediate value$975 a year
 A 13-Year Mortgage Paydown PlanPlanned mortgage paydown13 years
 A First Home and Family CoveredImmediate value$1,346 a year
 Age Pension Kept After an InheritanceProjected uplift at 90More than $642,000
Grow & Protect Your Wealth Today
Whatever’s on your mind, we’re here to help. You’ll speak with an authorised financial adviser who’ll listen first and get to know what matters to you.
Book An Initial Conversation