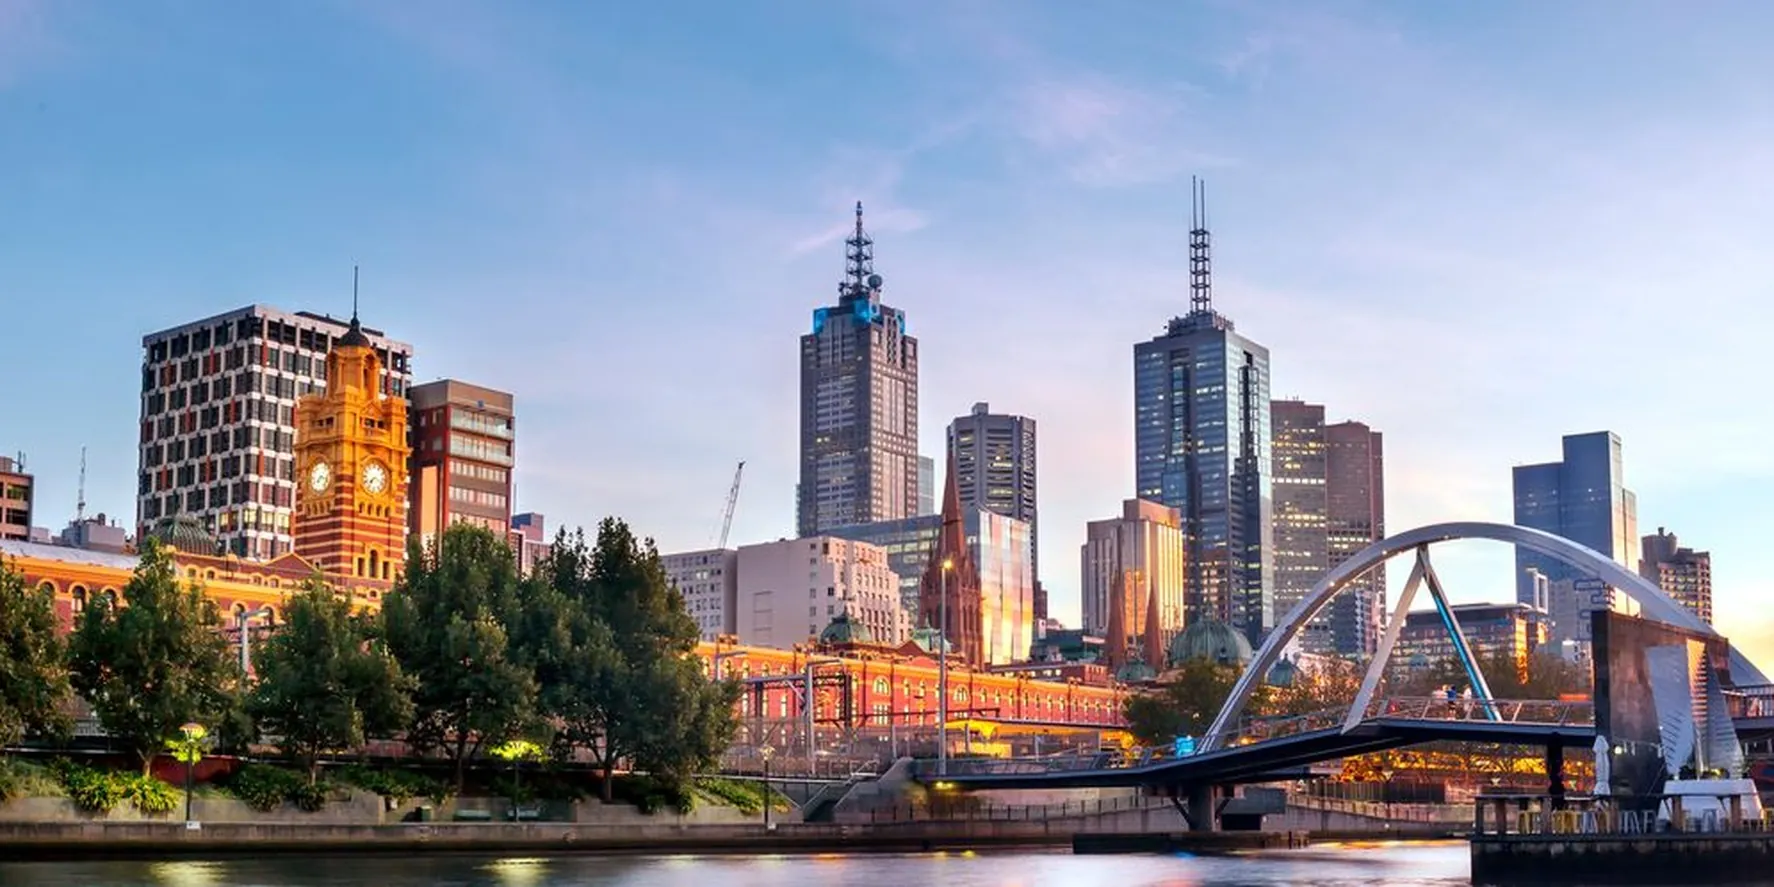
Financial Advisers and Planners in Melbourne
Empowering the Melbourne Community to Build Wealth and Prosperity
Rent or a home loan can shape how much room you have for cover, super, cashflow and tax. We help you weigh them up, at our St Kilda Road office or by phone or video.
Our Financial Advice Team Is Here to Help You
Who We Help
- Renters saving to buy with a deposit and the rent to manage at once
- Renters happy to rent and building wealth in other ways
- First home buyers adjusting to repayments for the first time
- Couples sharing one budget with rent or a loan to cover between them
- People new to Australia looking at super, insurance and a budget here
- Investors holding Victorian land with any land tax among their holding costs
- People close to retiring who may own or rent by the time they stop work
- Business owners with a lease at work, at home or both
We Can Help You
- Put rent or loan repayments at the top of a household budget
- Work out income protection from a budget that includes rent or repayments
- Plan saving for a home alongside super
- Decide whether life or TPD cover suits you, given any debts and dependants
- Plan retirement income, including what renting in retirement could cost
- Set tax strategy for investments and super, with an accountant preparing your return
- Look at an investment property as part of your plan, including any land tax
- Talk through the costs and trustee duties of an SMSF before setting one up
What we advise on
How We Can Help Across Melbourne
Cashflow & Financial Wellbeing
Before anything else, how much of your income goes to housing?
Seeing that figure clearly can show what’s left for saving and the life you’d like around it.
We’ll start your budget with what you pay for housing, then build the rest of your spending around it.
Housing costs fall due whatever else is happening, so we set them at the top of the budget and work down from there. A lease renewal, or a rate change if you have a loan, can be a useful prompt to run the numbers again. We agree on a buffer with you from your essential costs and income security, with no single target for every household.
Together, we’ll work through:
- Rent or loan repayments as the first line of the budget, with everyday costs set out beneath
- A lease renewal, and what a different rent could mean for savings and other goals
- Saving for a deposit alongside rent or other housing costs, if buying is on your list
- A cash buffer based on the weeks of housing and essential costs you’d want covered, with no fixed target
- Moving closer to work or further out, and what that could do to rent, transport and savings
- Sharing a home, and how rent and bills split when housemates or a partner change
- A rate move, if you have a home loan, and the room it would leave for savings
- Time between jobs or away from work, and which costs would carry on regardless
Financial Planning & Advice
Rent, buy or invest: which decision is on your mind first?
Looking at those choices together can show how each one affects your goals, and we’ll explain the options clearly.
We can build a financial plan, or Statement of Advice, that treats renting, buying and investing as connected decisions.
Every financial decision influences the next, so where you live can affect what you save, invest and insure. We don’t choose between renting and buying for you; we get to know your goals and income before we recommend anything, then set out your plan in writing and walk you through it.
Together, we’ll work through:
- Renting for longer and investing any difference, compared with buying sooner, with no single answer assumed
- Buying a first home, and the follow-on decisions about insurance and retirement saving
- Schools, work and family close by, and what living near them could cost
- A timeline for the decisions ahead, with the earliest ones set out first
- Deciding as a couple, where each of you may want something different from where you live
- Insurance help on its own, for anyone not looking for a complete set of recommendations
- Mortgage brokers, solicitors and other professionals you use, and how our work connects with theirs
- Beneficiary and will questions you may want to raise with a solicitor
Superannuation
Where does super fit alongside your housing costs or saving for a deposit?
Reading a fund’s fees, investments and any cover can show how super fits the years ahead, whatever your age.
We can go through a fund’s fees, investments and any cover, at whatever age you come to us.
When you start a new job, your employer generally pays into your existing super fund unless you choose another; a default fund applies only if you have no fund. From 1 July 2026 the general concessional cap is $32,500, and caps are indexed. We can compare extra contributions with saving for a deposit or other goals.
Together, we’ll work through:
- Spare money, if you have some, going towards a deposit first or super first, and what each could mean
- Contributions in years when rent or repayments take more of your pay, and what’s realistic for your budget
- Whether a renter with no dependants needs any cover a fund gives by default
- Two or more funds from past employers, and any insurance you’d lose or keep by merging them
- Savings or pensions held overseas, and the questions to take to an accountant before moving anything
- How a super balance is invested, given how far away retirement is for you
- Salary sacrificed into super in a year when money is less tight, within the yearly limit on pre-tax contributions
- Putting money in for a partner on a lower income or on leave, where the rules allow
Tax & Wealth Strategies
What part could tax play in what you save and invest?
Planning it alongside super and investments can show which choices suit the goals you’re working towards.
We’ll plan tax and set structure with you, working alongside an accountant, who prepares and lodges your return.
For gains accruing after 1 July 2027, indexation and a 30% minimum tax generally replace the 50% CGT discount. From 1 July 2027, negative gearing on residential property is limited to new builds, though property held on 12 May 2026 is exempt. If you hold or plan to buy an investment, we can work through those changes with you and an accountant.
Together, we’ll work through:
- Rent from an investment property, if you own one, and the deductions an accountant would confirm
- Earnings on money set aside for a deposit, and how an accountant would treat them
- Salary sacrifice compared with saving after tax for a deposit, with an accountant confirming your rate
- Division 293, the added tax on contributions for high earners, and what an accountant would confirm
- Anything you may sell after 1 July 2027, with an accountant working through the gain
- Arriving from overseas, and whether you’re a tax resident, confirmed by an accountant
- Contract or side income alongside your job, and what an accountant would want recorded
- Income from super once you retire, and the tax questions to raise with an accountant before then
Property Investment Advice
Does a rental property belong in your plans?
Testing rent, costs and any land tax against your budget can help you decide whether it suits you.
We can look at an investment property as part of your plan, and a mortgage broker handles the lending.
Victorian land tax starts at $50,000 of total taxable land holdings, on site value, for the 2024 to 2033 land tax years. Trusts differ and a principal place of residence exemption may apply; the State Revenue Office or an accountant can confirm. Borrowing to invest can magnify losses as well as gains, and the loan must still be repaid if values fall.
Together, we’ll work through:
- Rent as an investor’s income, set against interest, insurance, maintenance and any vacant weeks
- Any land tax counted with the other holding costs, which the State Revenue Office can confirm
- Total land holdings across more than one property, which is how Victorian land tax is worked out
- Holding an investment alone, jointly or in a trust, with an accountant advising on land tax and income tax
- Vacant weeks or a rate rise, and how long a buffer could carry the property
- Borrowing for an investment, where a mortgage broker works out what you may be able to borrow
- Renting where you live and owning an investment elsewhere, weighed up as one of your options
- A new build or an established property, and how the tax position differs, with an accountant
Learn more about Property Investment Advice
Source: State Revenue Office Victoria, land tax current rates
Retirement & Aged Care
What would retirement look like if you were still renting?
Working out rent, income and any Age Pension early can show what could support the life you’d like.
Together, we’ll plan for retirement whether you expect to rent, own outright or downsize.
Preservation age is 60 for anyone born from 1 July 1964, and super can generally only be accessed once you meet a condition of release, such as ceasing employment at 60 or over. Age Pension asset limits differ for homeowners and non-homeowners, and Rent Assistance may apply if you’re eligible, so we look at your housing first.
Together, we’ll work through:
- Rent in retirement as a budget line, if you expect to rent, and how long super and savings could support it
- Commonwealth Rent Assistance and what decides eligibility, confirmed with Services Australia
- Staying put in a home that’s paid off, and where your income would come from
- Selling a home and renting afterwards, and how the proceeds could affect your income and any Age Pension
- Turning super into a regular income, through an account-based pension where that suits you
- Staying in work for a while, part-time or full-time, with the Age Pension rules in mind
- A parent needing care, or your own plans for it, and how fees are worked out
- Who you’d like to leave money to, with a solicitor drafting the will
Personal Insurance & Protection
Who’d pay your housing costs if illness or injury stopped your income?
Income protection can pay part of your income once a policy’s definition and waiting period are met, which can help with housing.
We’ll work from your housing costs and, if cover suits, compare and apply with you; the insurer decides.
The median weekly rent for new lettings in metropolitan Melbourne was $595 in the June 2026 quarter. Any rent or loan of your own may be different, so we work from your figures. Moneysmart suggests a budget for sizing income protection, and life and TPD cover depend on any debts and who relies on your income.
Together, we’ll work through:
- Housing costs, bills and essentials added up first, then income protection sized within a policy’s limits
- Savings or leave measured in weeks of housing costs, which can guide a choice of waiting period
- Life cover and TPD, where someone depends on you or debts would need clearing
- A renter with no dependants, who may need less life cover than a household with children or a loan
- Insurance your fund provides, if any, and what the premiums cost you each year
- Whether trauma cover is worth considering at all for your household, with its definitions read first
- Your application, answered with reasonable care, and what could happen after the insurer reads it
- Older policies, if you hold any, kept in view until you know what a change would mean
Income Protection with a Health Condition or Illness
Could a health condition change the cover an insurer offers you?
Our guides explain what insurers may ask about common conditions, and a health condition doesn’t necessarily rule out cover.
We can help you prepare an application with a health condition or past illness, and the insurer decides whether to offer cover.
- Cover with a health condition: where to start
- Autoimmune conditions
- Back or joint conditions
- Blood conditions
- Cancer history
- Diabetes
- Digestive conditions
- Eye or hearing conditions
- Heart conditions
- HIV or hepatitis
- Kidney conditions
- Mental health conditions
- Neurological conditions
- Respiratory or sleep conditions
- Weight, smoking or alcohol history
- Women’s health conditions
SMSF
Would you like more say over how your super is invested?
Talking through time, cost and duties can help you decide whether a self-managed fund suits you.
We’ll go through whether a self-managed fund suits your balance, time and goals, and what else could do the job.
A self-managed fund gives you more control, along with running costs, administration and legal duties as a trustee. Leaving an APRA-regulated fund means losing the benefits of prudential regulation and the ability to complain about the fund to AFCA. We can compare it with investment choices inside an existing fund.
Together, we’ll work through:
- The starting balance you’d bring, and how a fund’s yearly costs would compare with it
- Shares, term deposits or other investments a fund could hold under a documented investment strategy
- Paperwork a trustee takes on each year, from minutes to the audit and accounts
- What leaving APRA regulation would mean for how a complaint about the fund is handled
- Any life or income cover through your present fund, and what keeping it elsewhere might cost
- Who else might join the fund, and how each person’s share would be recorded
- An existing SMSF, looked at for investments, yearly costs and what you’d like from retirement
- Time away, illness or moving overseas, and who would keep the fund running in that case
Areas of Melbourne We Service
Is an office visit or a call better for you?
Either way, we’ll start with what’s on your mind and what you’d like from the years ahead.
We can meet you at our St Kilda Road office, or by phone or video, from anywhere in Melbourne.
Our Melbourne office:
- Level 5, 380 St Kilda Road, Melbourne VIC 3000
The regions we service:
- Melbourne CBD and Inner City, including Carlton, North Melbourne, Fitzroy, Richmond, South Melbourne, St Kilda and surrounding suburbs
- Bayside, Inner South East and Inner East, including Prahran, Toorak, Caulfield, Brighton, Hawthorn, Camberwell and surrounding suburbs
- Eastern Suburbs, including Box Hill, Doncaster, Glen Waverley, Ringwood, Bayswater, Lilydale and surrounding suburbs
- South East Melbourne, including Springvale, Dandenong, Narre Warren, Berwick, Cranbourne, Pakenham and surrounding suburbs
- Kingston, Frankston and the Mornington Peninsula, including Moorabbin, Mentone, Seaford, Mount Eliza, Mornington, Rosebud and surrounding suburbs
- Inner West, including Footscray, Yarraville, Williamstown, Altona, Essendon, Moonee Ponds and surrounding suburbs
- Outer West, including St Albans, Caroline Springs, Melton, Werribee, Hoppers Crossing, Point Cook, Tarneit and surrounding suburbs
- Northern Suburbs, including Brunswick, Coburg, Preston, Ivanhoe, Eltham, Epping, South Morang, Craigieburn, Sunbury and surrounding suburbs
Where Our Advice Can Help
Rent or Repayments First
Build a budget that starts with your housing cost and shows what’s left.
Income Protection and Housing
See how income protection could fit with your housing costs, within a policy’s terms.
Saving to Buy
Set a deposit goal alongside your housing costs, super and the other things you’re planning for.
Super Beside Your Housing
See how contributions and any fund cover could fit around your housing costs.
Tax on Investments
Plan structure and strategy for investments, with an accountant preparing and lodging your return.
Land Tax in the Numbers
See how any land tax and other costs could affect an investment property plan.
Renting in Retirement
Plan the income you’d like if you expect to be renting after you stop work.
Starting Out in Australia
Look at super, insurance and a budget that suit your plans after moving here.
Proactive, Holistic, and Experienced Financial Planning
Rent or loan repayments are often the first thing a budget has to cover, and they can shape the choices that follow. Renting, saving for a first home or settling into new repayments can each feel like quite a lot to carry. We listen to what you’d like from life, explain your options clearly and help you build a financial plan around your housing and what you care about most.
Perhaps your home is already paid off, or you’ve just arrived in a new country, or retirement is simply the next thing on your mind. Whichever it is, you and anyone you plan for deserve the same care. We can help you plan for the years ahead, with room for the people and goals that mean the most to you, and we’re glad to start from where you are today.
Every financial decision impacts the next
Your Financial Life Is Connected
Great advice starts with understanding the bigger picture. Every stage of life presents new opportunities and challenges, from buying property and changing careers to growing your family, planning for retirement and protecting what matters most. At Ryker, we help connect every piece of your financial world into one clear strategy.
Your
Wealth
- Property & Investing
- Career & Income
- Tax Strategy
- Insurance & Protecting Your Family
- Super & SMSF
- Wealth & Investments
- Life Events & Changes
- Business & Wealth
- Legacy & Future Wealth
- Retirement Planning
Financial Advice for Everyone
Frequently Asked Questions
We’re invested in your long-term success. What we do is personal, and we take it personally.
Your financial decisions connect, so we consider the parts of your financial life that are relevant to the advice you need:
- Property & Investing
- Career & Income
- Tax Strategy
- Insurance & Protecting Your Family
- Super & SMSF
- Wealth & Investments
- Life Events & Changes
- Business & Wealth
- Legacy & Future Wealth
- Retirement Planning
This is how we help you make decisions today with your longer-term goals in view.
Everybody’s situation is different, so we listen first, understand what matters to you and explain your options clearly before we make a recommendation.
It depends on who relies on your income, any debts you have and what you’d need to keep paying if illness or injury stopped you working. Cover isn’t only for people with a home loan, and it isn’t right for everyone: a renter with no dependants may need less than a family does.
We can look at any cover you already hold, including in super, and compare and apply for more with you if it suits. The insurer decides whether to offer cover and on what terms.
Your accountant and financial adviser bring different expertise to the same decisions. Your accountant can advise on tax reporting, structures and consequences; we help you plan how cashflow, debt, super, investments and protection work towards your goals. We can coordinate before important decisions.
What an accountant does
- Prepares and lodges tax returns, BAS and financial statements
- Advises on tax structures such as companies, trusts and partnerships
- Manages bookkeeping, payroll and ATO compliance
- Provides tax advice on the consequences of a transaction
What a financial adviser does
- Sets a long term strategy across retirement, investing and cash flow
- Builds wealth from early in a working life, starting with cash flow, a first home and super
- Recommends specific super funds, investments and personal insurance
- Operates under an Australian Financial Services Licence, which is required to give personal advice on financial products
- Handles retirement planning, Centrelink and aged care strategy, and estate planning considerations
Professional roles and authorisations matter. We provide financial advice within our authorisations and work with your accountant for specialist tax advice and lodgements.
Where they work together
- Tax position. Your accountant confirms your marginal rate, deductions and carried forward losses, which shapes decisions on super contributions, investment structures and the timing of asset sales.
- Business and entity structures. Your accountant advises on the structure itself and your financial adviser works within it for investments, insurance and succession planning.
- Cash flow. Your accountant’s figures can help us understand what’s available for debt repayment, protection and longer-term goals.
- Before key decisions. We can coordinate with your accountant on contributions, asset sales and other material choices in time to consider relevant tax consequences.
It can, and that’s where our local knowledge helps. We know Melbourne’s local government areas, from the City of Melbourne out to Wyndham, Casey and the Mornington Peninsula, how property values have moved from suburb to suburb, its multicultural communities and the opportunities a thriving economy can bring. You can meet us at our St Kilda Road office, or by phone or video from anywhere in the city.
The rules on super and the Age Pension are national, so they stay the same wherever you live here. Your advice starts with your own situation and plans.
There isn’t one answer, and we won’t make the choice for you. We’d compare what you pay in rent with what owning could cost, how much a deposit would take from savings, what you’d like from the next few years and how long you expect to stay.
How much you can borrow is a question for a mortgage broker, and we don’t forecast rents or prices. We can then show how each path could fit your plan.
We don’t have an office in Werribee, and you don’t have to come in. You can meet us at our St Kilda Road office in Melbourne, or by phone or video, whichever suits you.
However we meet, we’ll start with what’s on your mind, then explain how we can help and what we’ll need to get started.
It starts with a budget, as Moneysmart suggests: your rent, bills and other costs that would carry on if illness or injury stopped you working. Any savings, leave or other support can help with the gap.
A policy usually replaces a percentage of your pre-tax income once its definition and waiting period are met, so the budget and the policy limit both matter. We can compare options and, if cover suits, apply with you, and the insurer decides.
Quotes from a comparison site can be a useful starting point, based on the questions it asks.
A renter’s budget is where advice begins: what you pay each week, any debts and whether anyone depends on you. From there, we’d go through a policy’s wording and help with the application, though the decision sits with the insurer. There’s no cost for the initial conversation. Any advice after that is a paid service, with its scope and fee agreed with you in writing first.
Land tax is one of the holding costs we’d set against any rent and your other goals. In Victoria it’s worked out on the site value of your total taxable land holdings, so more than one property can matter, and trusts are treated differently.
The State Revenue Office or an accountant can confirm your own position, including any exemption. We can then look at how the property fits your wider plan.
A simple budget is a good place to start, then super and any cover you have. Employers generally pay super for eligible employees, and it helps to know which fund it’s going to and whether any insurance comes with it.
Money or pensions held overseas, and tax residency, are questions for an accountant. We can then work through your goals with you, including whether you’d like to rent or buy.
Rent stays in the budget for as long as you rent, so we plan income with that in view. Age Pension asset limits differ for homeowners and non-homeowners, and Rent Assistance may apply if you’re eligible, which Services Australia can confirm.
We can work through how long super and savings could support the rent and what you’d like to do with your time, before and after you stop work.
Your home gives you somewhere to live, and your income generally has to come from elsewhere unless you sell or downsize. We’d start with what any super, savings and investments could pay you each year, and how you’d like to spend your time.
We’d also look at whether any cover still suits you, whether to stay or move, and estate plans to take to a solicitor. Super generally can’t be accessed until you meet a condition of release.
There’s no cost for the initial conversation. Any advice after that is a paid service, with its scope and fee agreed with you in writing first.
In that first conversation we’ll explain how we can help and what we’ll need to get started, and you’re welcome to ask anything about how our fees work.
You can meet us at our St Kilda Road office or by phone or video. The areas tab above lists the regions we service.
Our services are financial planning and advice, personal insurance, superannuation, SMSF, cashflow and financial wellbeing, tax and wealth strategies, property investment advice, and retirement and aged care. Each one has its own page with more detail, linked from the tabs above.
Lending goes to a mortgage broker, tax returns to an accountant and wills to a solicitor, and we can work alongside them.
Our first conversation starts with what you’d like to talk about, whether that’s rent, a first home, a new arrival in the family or life after work.
There’s no cost for the initial conversation. Any advice after that is a paid service, with its scope and fee agreed with you in writing first. To get started, it helps to have a recent payslip, a lease or loan statement and a super statement, if you have them, and we’ll walk you through what happens next.
Reviews
Testimonials from Our Clients
Client Success Stories
 A Property Sale Became a Full PlanEstimated long term financial benefitApprox $448,000
 A Plan to Keep the Family HomeLife cover established$1.2 Million
 Cover in Place and Fees LoweredImmediate value$1,055 a year
 Super Fees More than HalvedProjected retirement uplift$416k
 Income Covered for a New MortgageImmediate value$975 a year
 A 13-Year Mortgage Paydown PlanPlanned mortgage paydown13 years
 A First Home and Family CoveredImmediate value$1,346 a year
 Age Pension Kept After an InheritanceProjected uplift at 90More than $642,000
Grow & Protect Your Wealth Today
Whatever’s on your mind, we’re here to help. You’ll speak with an authorised financial adviser who’ll listen first and get to know what matters to you.
Book An Initial Conversation