
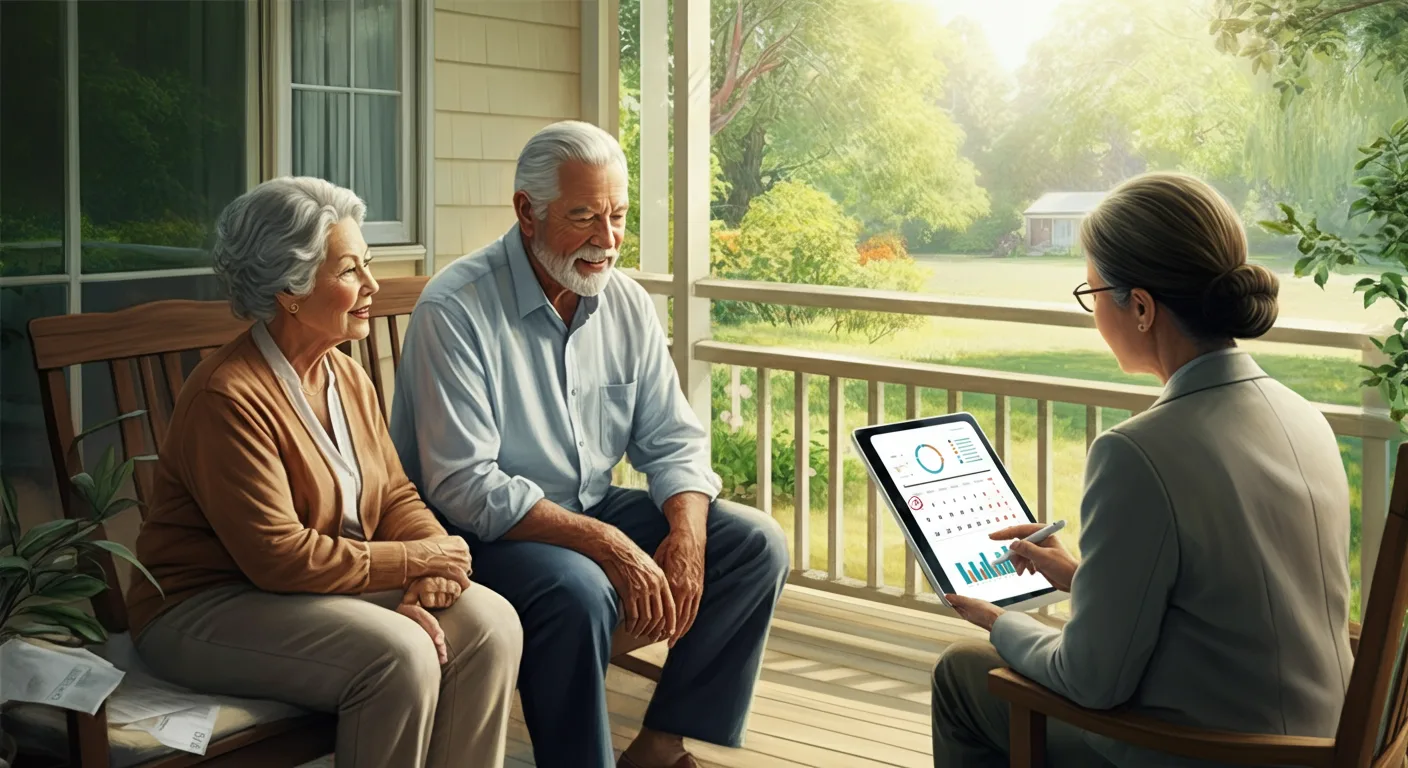
While older Australians have been long in the tooth in terms of their expected life spans, the same holds true for revisionist approaches to retirement and financial planning. Life expectancy is no longer just a number, it’s a comprehensive, dynamic concept that affects how we save, invest, and plan for the future. This blog dissects life expectancy and will show retirees how they can navigate financial risks and create stronger retirement preparations.
Understanding Life Expectancy: A Dynamic Outlook
However, life expectancy seems like a fixed number. Usually, it is averaged out to produce a single number, which does not really get into the meat of the person’s probability of survival. Life expectancy increases even as a person gets older. If a person attains the age of 65, for instance, they will have a higher life expectancy than what it was at birth because of less risk to survival in early life and medical advancements that make a longer life possible.
- Such an antiquated point of view leads to two critical planning errors.
- Running out of money too early: Underestimating longevity causes retirees to exhaust their savings well before they die.
- Overestimating longevity may cause people to spend too little on themselves, restricting their lifestyle and fun in retirement.
Indeed, it is essential to rethink life expectancy. It is time Australia stopped thinking that life expectancy is just about how long one has lived, and rather thought about how finances will support living across those years.
Retirement Planning and Life Expectancy: What’s at Stake?
The Misconception of Life Expectancy
In reality, financial advisers are often dealing with retirees who base calculations on average life expectancies. There are deviations, however, that come into play. To cite just one example, according to the Australian Bureau of Statistics, a male in Australia can expect to live to about 81 years of age, and a female about 85 years. Clearly, a good many people will live far beyond these averages.
The Risk of Misplanning
There are numerous risks associated with misplanning, and failing to grasp the nuances of life expectancy can lead to
- Premature depletion of retirement funds
- Excessive savings with underused wealth
- Stressful financial decision-making in older age
Retirees must create financial plans incorporating probabilistic projections and adaptable income approaches to prevent foreseeable retirement problems.
Navigating Financial Risks in Retirement:
Living Longer Brings Not Just Opportunities but Significant Financial Risks. Let’s Explore the Key Ones:
Sequencing Risk
It is the risk of having poor investment returns early in retirement. For instance, drawing money during a market decline can greatly lower the total value of a retirement portfolio.
Example: A retiree drawing $50,000 a year from a $1 million portfolio that falls by 20% in a downturn may run through their money quicker than anticipated.
Solution: Diversifying the investment choices and varying withdrawal techniques can be beneficial.
Market Volatility
Unstable markets can affect retirement funds if not handled well. Retirees require stable returns and income predictability.
Solution: A diversified portfolio with a combination of equities, bonds, and cash.
Inflation Risk
Inflation gradually wears away purchasing power. In a 20- to 30-year retirement, even modest inflation rates can make a significant difference to living standards.
Solution: Inflation-linked investments or varying annual spending limits.
Behavioural Biases
Retirees can panic in downturns or be overconfident in rising markets.
Example: Panic-selling in a market crash.
Solution: Work with a financial adviser to create a long-term plan and resist emotional choices.
Lifetime Income Streams: Do They Solve the Problem?
Lifetime income products (such as annuities) guarantee stable payments and worry-free living. They are sold as a longevity risk solution, but are they an ideal solution?
Advantages:
Predictability: Stable payments despite market fluctuations.
Simplicity: Active investment management is not required.
Peace of Mind: Eliminates anxiety about outliving savings.
Disadvantages:
Lack of Flexibility: Money is frequently tied up.
Concerns Over Inflation: Stable income may not compensate for increasing expenses.
Complexity: May be hard to grasp without professional assistance.
Experts advise employing lifetime income streams as one component of an overall, diversified retirement strategy and not as a one-size-fits-all plan.
Retirement Strategy: What to Do?
To create a robust, future-proof retirement plan, consider the following:
- Personalized Planning: Make decisions on your life expectancy and financial objectives.
- Flexible Income Sources: Blend superannuation, pensions, annuities, and investments.
- Professional Guidance: Join forces with an experienced financial planner.
- Regular Reviews: Review your plan as your needs and market conditions evolve.
Conclusion:
Australians now have to contend with a retirement that will last 30+ years. Redefining life expectancy and planning for risks isn’t intelligent—it’s unavoidable. A combination of tailored planning, adaptable approaches, and continuing advice guarantees retirees can live out their golden years without financial worry.
More From Our Advisers
View all articles →

Grow & Protect Your Wealth Today
Whatever’s on your mind, we’re here to help. You’ll speak with an authorised financial adviser who’ll listen first and get to know what matters to you.
Book An Initial Conversation