
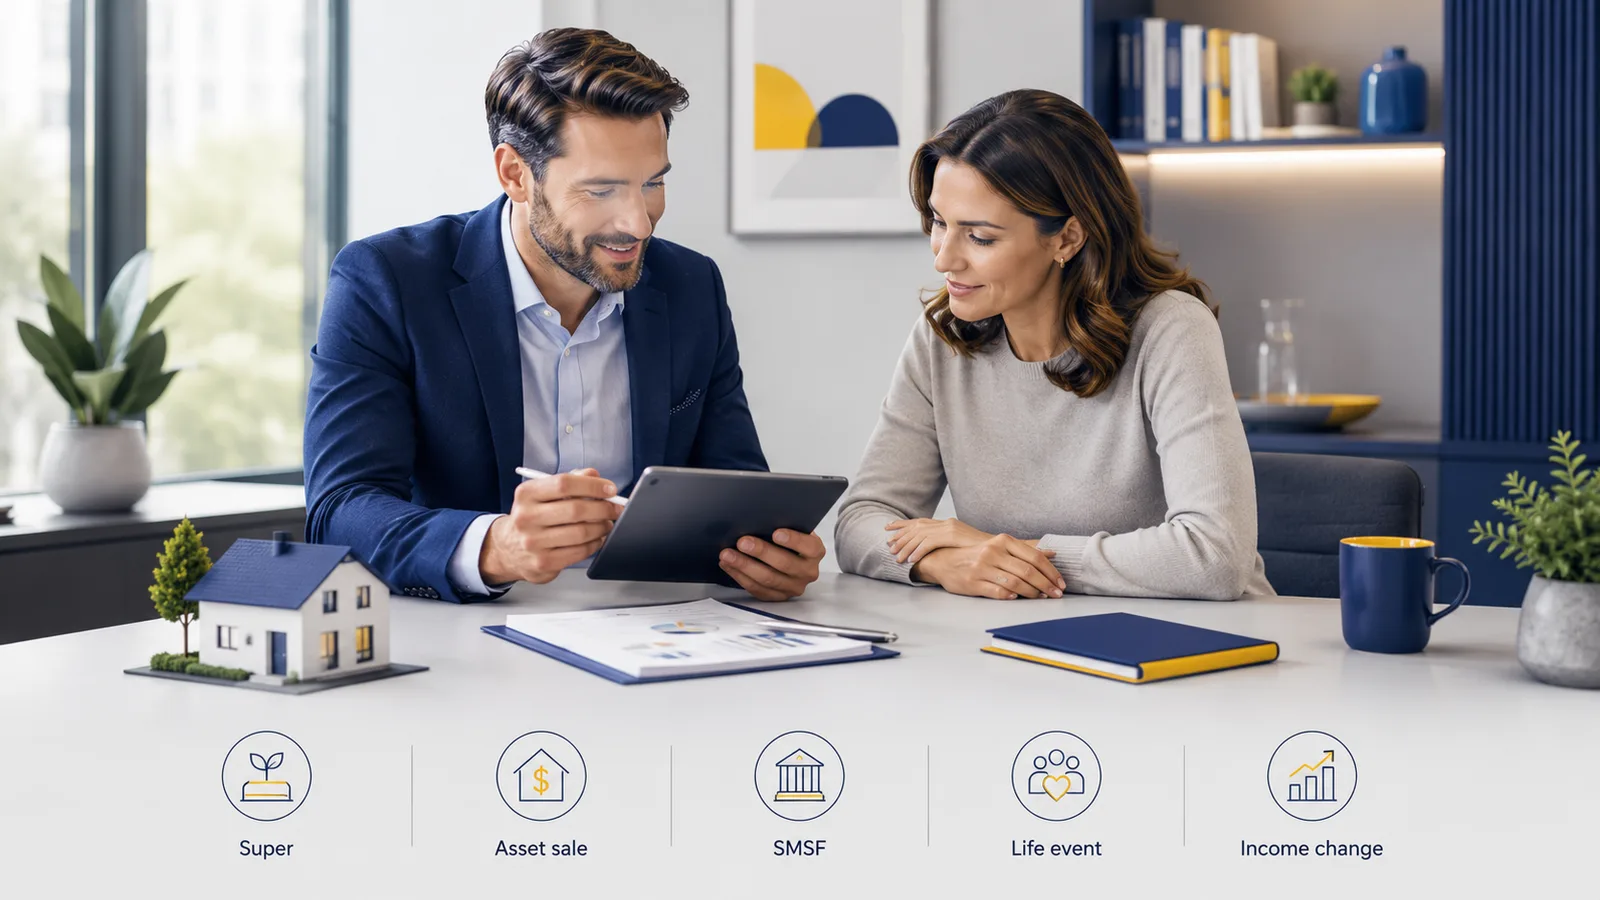
The loan application sees everything. Here is how to turn what you see into more value for your client.
A home loan application is one of the most revealing documents in a person’s financial life. As a broker, you see the super balance, the income, the assets, the debts and the life stage all at once. Most of that detail is used for the loan and then set aside. But buried in it are clear signals that your client needs advice you are not licensed to give. Spot them, and you become far more than the person who got them a rate. And with the federal budget and the 1 July super changes reshaping several of these moments, spotting them has never mattered more.
1. A Super Balance Surfaces in the Application
You see a super statement during the loan. If the balance is large, or oddly small for the client’s age, or sitting in a fund that may no longer suit their circumstances, that is a conversation for an adviser. You do not advise, you introduce.
2. They Have Just Sold, or Are About to Sell, an Asset
A sale of an investment property or a business releases money that needs a plan, and almost always has tax consequences. With the negative gearing and capital gains tax reforms now passed by Parliament and commencing 1 July 2027 (ATO), the timing and structure of a sale matter more than they used to. The moment it comes up is the moment to bring in a partner.
3. They Are Asking About Buying Through an SMSF
This is the one that has just changed in a big way. New borrowing to buy residential property inside a self-managed fund has been banned, a change that became law in late June 2026 and applies to new arrangements from 10 August 2026, with existing residential arrangements grandfathered and commercial property borrowing unaffected (SMSF Adviser). A client asking about an SMSF purchase now needs current advice before they act, not a strategy that worked last year. It is a clear signal to bring in an adviser alongside the lending.
4. A Major Life Event Is in the File
Marriage, separation, a new child, a death in the family, a serious illness. Each reshapes a financial plan, and each is a moment a client values being looked after, not just financed.
5. Their Income or Structure Has Changed
A new business, a jump in income, a move to contracting. The structure that worked last year may not fit now, and that is an advice question, not a lending one.
Turning the Signal into Value
Brokers are diversifying the value they offer clients (FBAA, 2026), and a referral partnership is the cleanest way to do it without leaving your lane. You keep doing what you do best. When you spot one of these moments, you hand the client to a partner who looks after them and sends them back to you.
For Brokers
Want a simple one-pager of these trigger moments to keep by your desk? We will send you the broker version. No strings attached, just a useful tool for your next application.
Ryker Broker Brochure 2024 (internal reference) · FBAA Newshub, 2026 (broker diversification and opportunities) · SMSF Adviser, SMSF residential property borrowing (LRBA) ban, law June 2026 · ATO, Reforming negative gearing and capital gains tax (law, commences 1 July 2027)
Contact Us
The information in this article is general in nature and does not take into account your personal objectives, financial situation or needs. Before acting on any information, you should consider whether it is appropriate for your individual circumstances and seek professional advice.
More From Our Advisers
View all articles →

Grow & Protect Your Wealth Today
Whatever’s on your mind, we’re here to help. You’ll speak with an authorised financial adviser who’ll listen first and get to know what matters to you.
Book An Initial Conversation